Insurance for farms and primary producers
Farms, orchards, vineyards and livestock operations combine a home, a business, heavy machinery and land the public walks across. One policy rarely covers all four, and the gaps show up after a fire or a flood.
The homestead, the machinery and the people who come onto the land
Property Insurance
Homestead, sheds, fencing, hay and stored produce, with farm machinery and irrigation on a schedule at replacement value.
Property coverPublic & Products Liability
Injury and property damage to visitors, contractors, agistment clients and neighbours, including straying stock and spray drift where cover can be arranged.
Liability coverMotor Fleet
Farm vehicles, utes, trucks and registered machinery on one policy, including the trip to the saleyards and the season's contract work.
Motor Fleet coverThe policy lists what was declared, at the values declared
Farm packs are built from sections, and each section only covers what is written into it.
Fencing and hay
Fencing is often insured only for storm and fire, and hay only in named stacks. After a bushfire the claim is limited to what was declared, at the values declared.
Machinery
Headers, tractors and pivots are insured for their scheduled value. A machine bought mid-season, or upgraded, is on the policy only once the insurer is told.
Contractors and workers
Seasonal labour, contractors and family members all need workers compensation or personal accident cover. A serious injury during harvest is where the gap becomes expensive.
A shed fire in the middle of seeding
An illustrative example of how Ardent can make the difference in a time of need.
A machinery shed burnt down overnight, taking a tractor, an air seeder and the workshop with it. The loss landed in the fortnight when that machinery was needed most.
We had the plant scheduled at replacement value with hire of substitute machinery included, and got the insurer to authorise hired equipment within days rather than waiting on the full assessment.
Seeding was finished on time with hired plant. The shed and the machinery were replaced, and the hire costs came out of the policy.
Responds under Machinery Breakdown
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
What insurers expect to see
Farm policies are rated on the sections you select and the values you declare. We go through the schedule with you each year so what stands on the property is what the policy lists.
- Machinery and vehicles listed with current values, including mid-season purchases
- Fencing length and hay quantities declared, with the perils that matter to your region selected
- Livestock cover matched to the numbers held and the transit you use
- Public liability that includes agistment, farm stays and any public access
- Workers compensation across permanent, seasonal and contract labour
- Loss of income for a lost season, where cover is available for your crop or stock
Our Agriculture experts
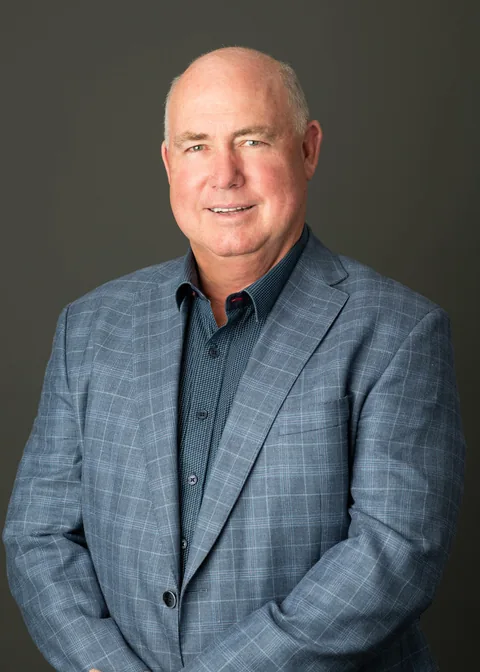
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Mining, aviation, construction, retail and property
Steve has 40 years in insurance, most of it in construction and civil engineering, with underground mining, aviation, national retail and property development alongside. He is one of Ardent's founders, works from inside a client's business and keeps those relationships for the long term.
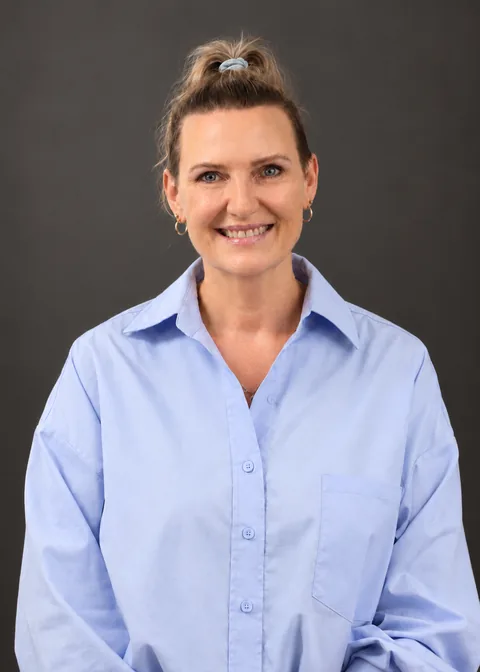
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
QPIB · Dip. Fin. Serv. (Ins Broking) · Dip. Integrated Risk Management · ANZIIF (Snr Assoc) CIP
Risk management and program design
Stephen co-founded Ardent and has 17 years in insurance, with clients from sole traders to multinational corporates. He works through the risks a business faces and helps decide what to avoid, reduce, retain or insure, balancing cover against cost. He has served on the committee of NIBA's NSW Mentoring Program.
What a client says about Ardent
Excellent service with competitive and tailored insurance premiums