Private Vault Insurance
Private vault storage provides physical security. It does not provide insurance. Assets held in a personal or commercial vault remain uninsured unless a specific policy is in place. Ardent arranges Private Vault cover for collections of precious metals, bullion, jewellery, fine art, rare collectibles, and documents, with agreed values and terms that reflect what you're storing.
What you keep in the vault, insured in your own name
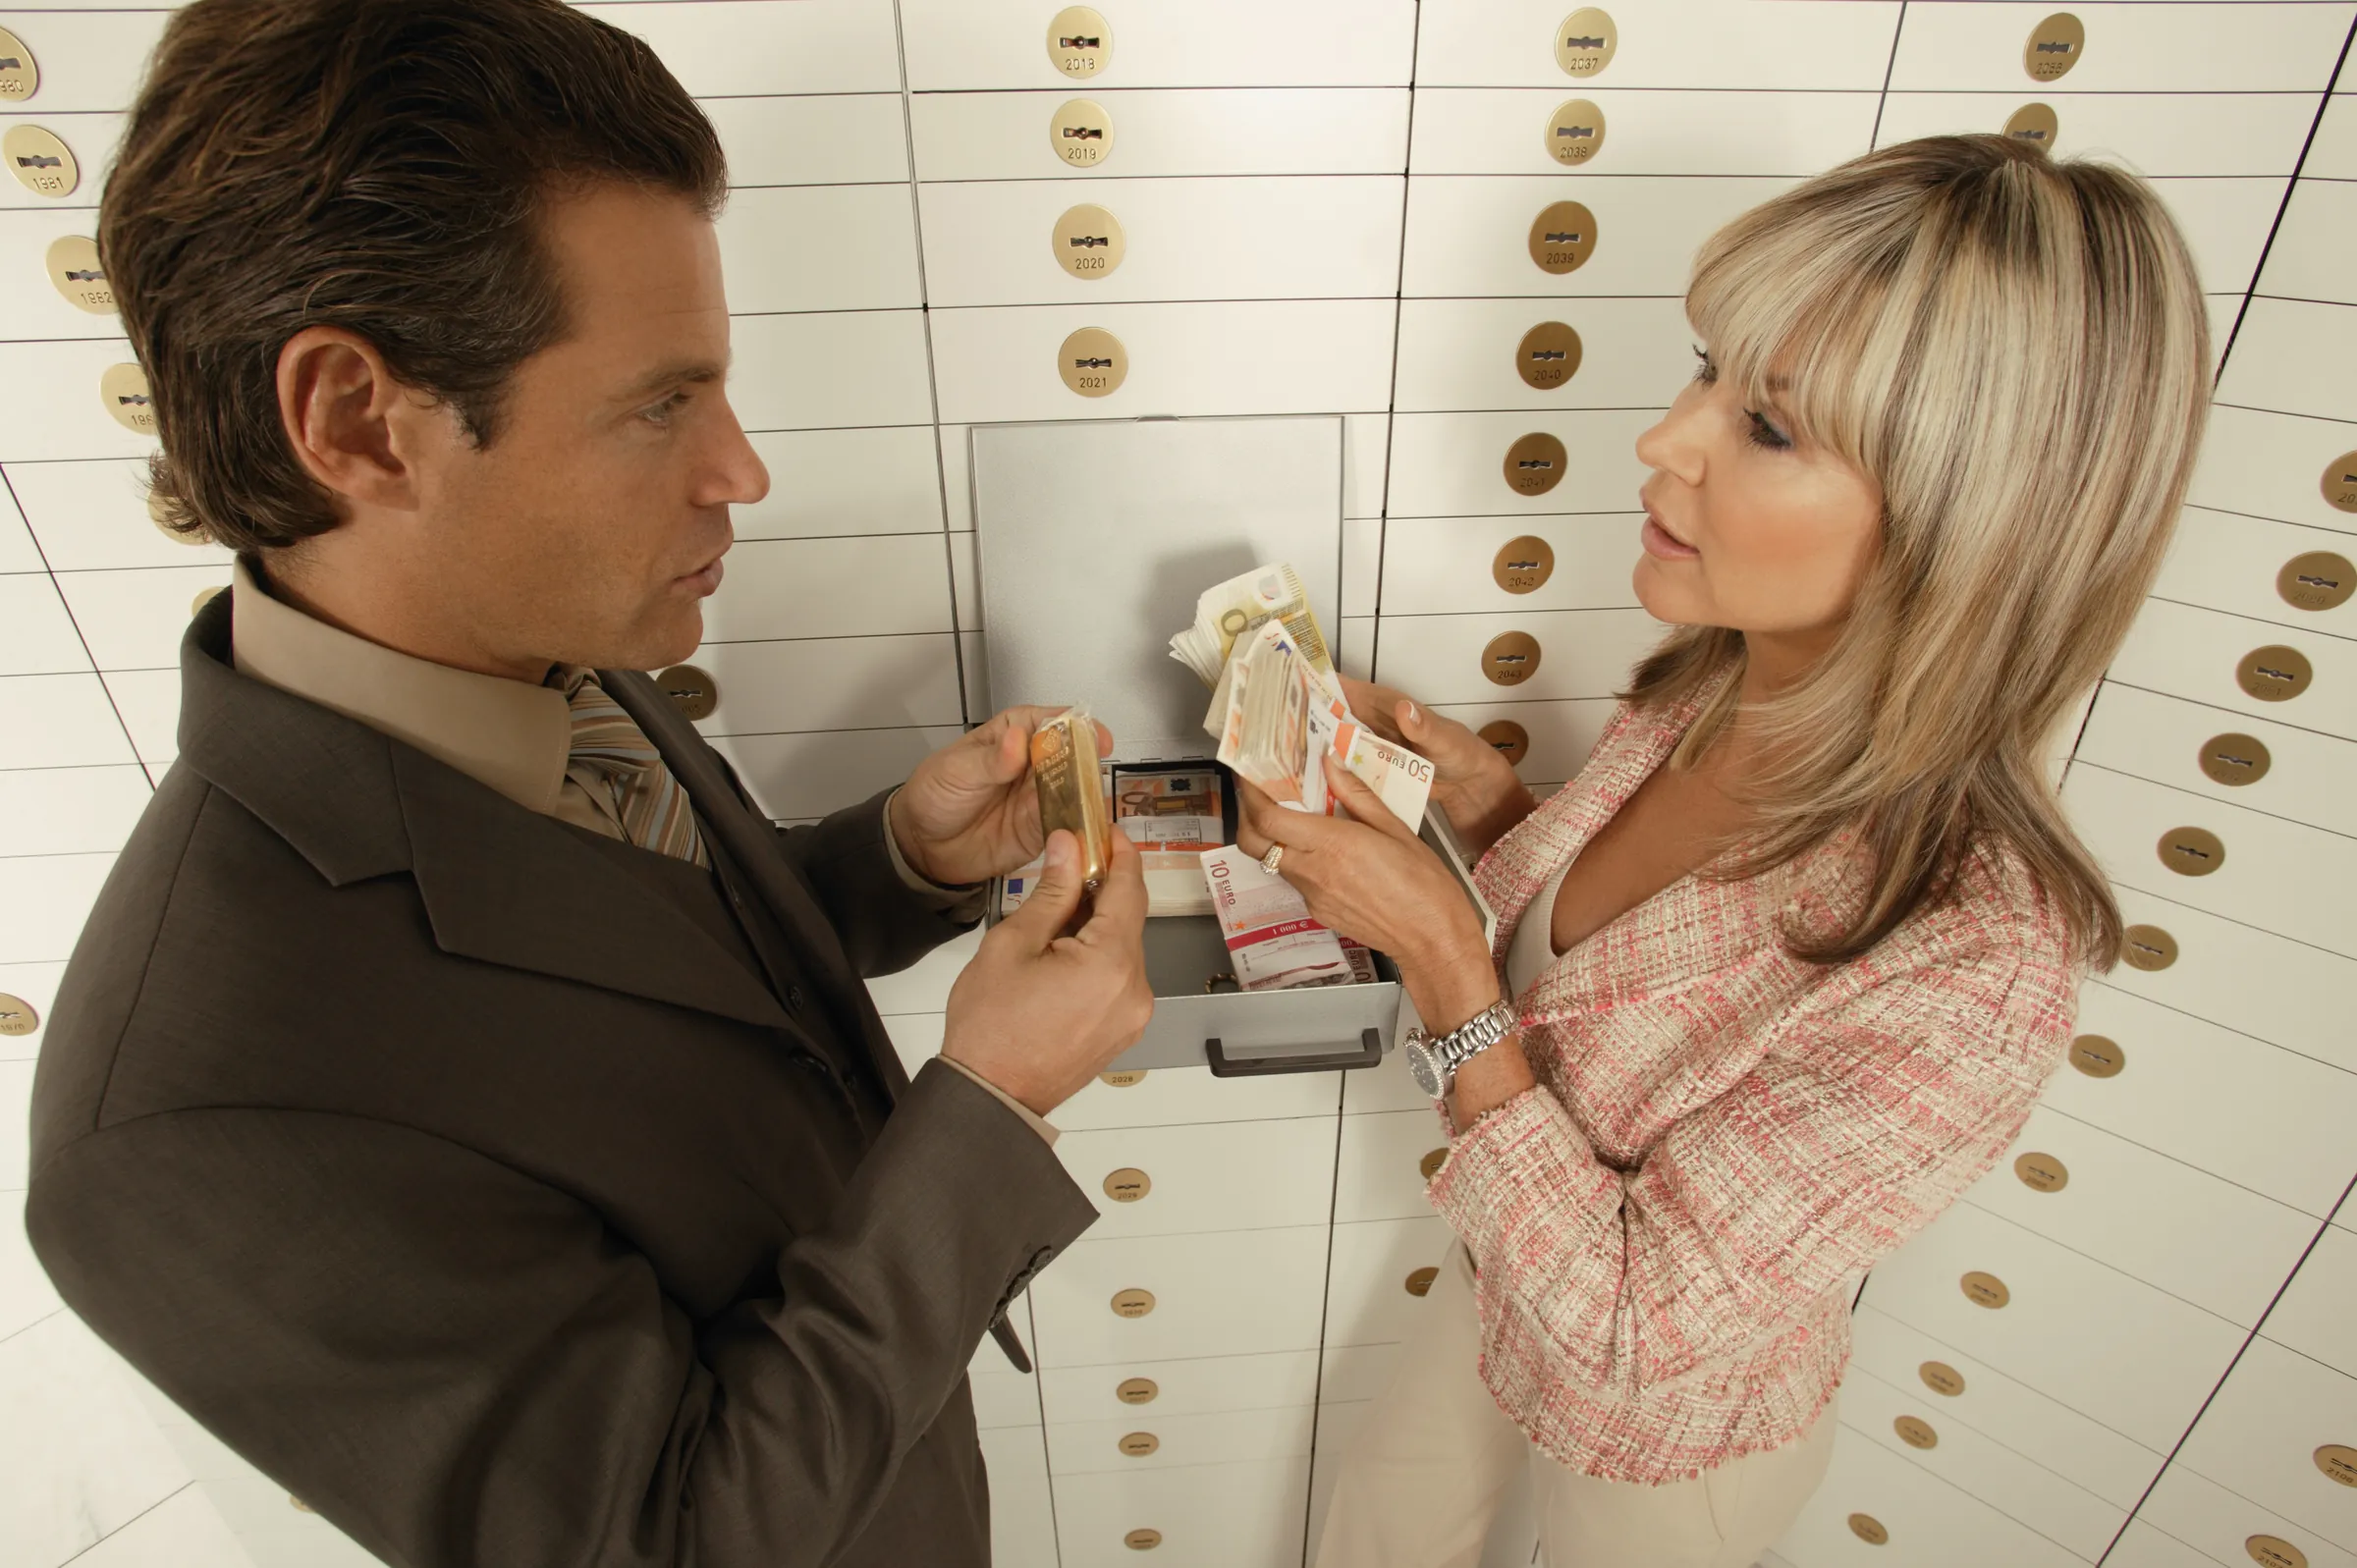
A collection in a vault, and a facility that only insured its own negligence
An illustrative example of how Ardent can make the difference in a time of need.
A private vault facility suffered a loss affecting several boxes. The facility's own policy covered its legal liability, which meant proving negligence and a cap well below the value held.
The client held a Private Vault policy in their own name with agreed values on the scheduled items, arranged after we read the facility's terms and conditions.
The client was paid the agreed values without having to establish negligence against the facility or wait on that dispute to resolve.
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
Our Private Vault experts
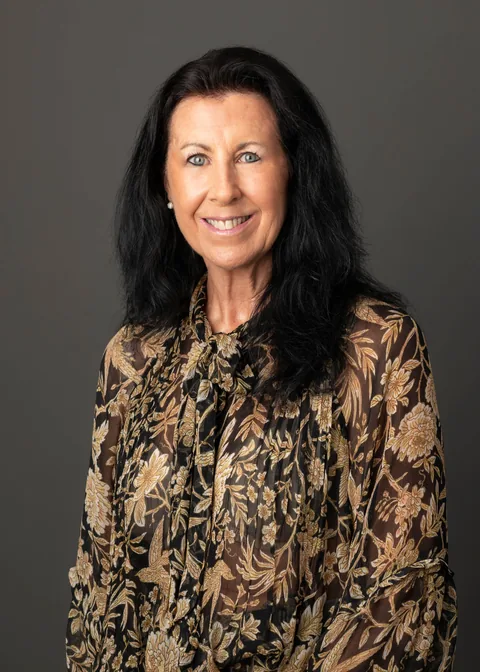
QPIB · Dip. Fin. Serv. (Ins Broking)
Client relationships and team leadership
Lynne co-founded Ardent after 45 years in insurance broking, and strong client relationships have run through all of it. In recent years she has worked as a General Manager, bringing general broking experience together with managing a team. At Ardent she supports the staff and keeps the workplace positive, which clients feel in every dealing they have with us.
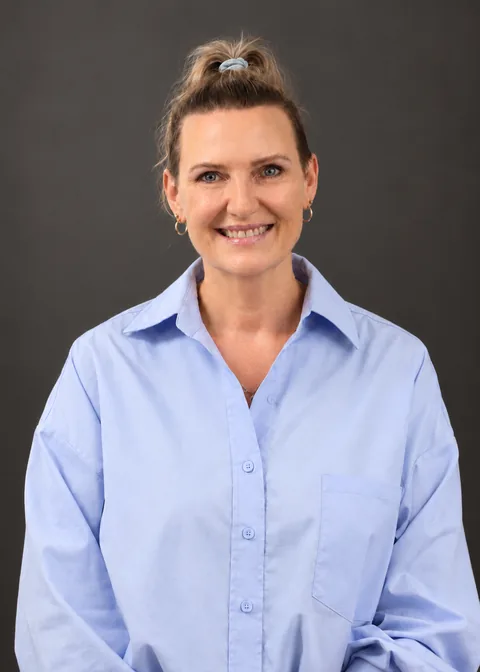
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
Mid-market businesses and jewellers
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
What a client says about Ardent
Dealing with Sophie Hudson has been a pleasure.
Private Vault FAQ
Vault facilities carry their own insurance, but this typically covers only their legal liability for loss or damage, not the full replacement value of what is stored. In practice, a vault's public liability policy may cover only a fraction of the value of your holdings, and the claim process involves proving the facility was negligent, which is difficult. A Private Vault policy insures your assets directly and on an agreed value basis, so recovery generally does not depend on proving fault by the vault operator, subject to the policy terms. Many vault users do not discover this until they try to make a claim.
For higher-value items (fine art, individual pieces of jewellery, rare collectibles), independent valuations are recommended and often required by underwriters. Precious metals can generally be insured based on market value at inception with automatic market value adjustment provisions, but collections of jewellery, art, and collectibles should be individually specified with formal valuations so the agreed value is clear at claim time. Ardent can connect you with specialist valuers for all asset categories and checks that each valuation is structured to suit the policy it will support. We may receive a fee or commission for a referral, as our Financial Services Guide explains.
Yes. A single Private Vault policy can cover assets across multiple storage locations. Each location is listed on the policy schedule with the values held there, and sub-limits can be applied per location if required. This is common for clients with assets distributed across, for example, a vault in Sydney, a specialist art storage facility in Melbourne, and overseas storage. Ardent keeps the policy schedule accurate about where assets are held, so cover responds correctly whichever location suffers a loss.
For precious metals, the insured value can be structured as a fixed agreed value (reviewed at renewal) or as a market value policy that adjusts automatically based on a recognised market index. Market value policies are generally preferable for metals given price volatility, but they require agreement on the valuation methodology (spot price, weighted average, specific exchange price). Ardent structures precious metal policies to avoid the situation where a significant increase in gold or silver prices leaves the insured value materially below replacement value at claim time.