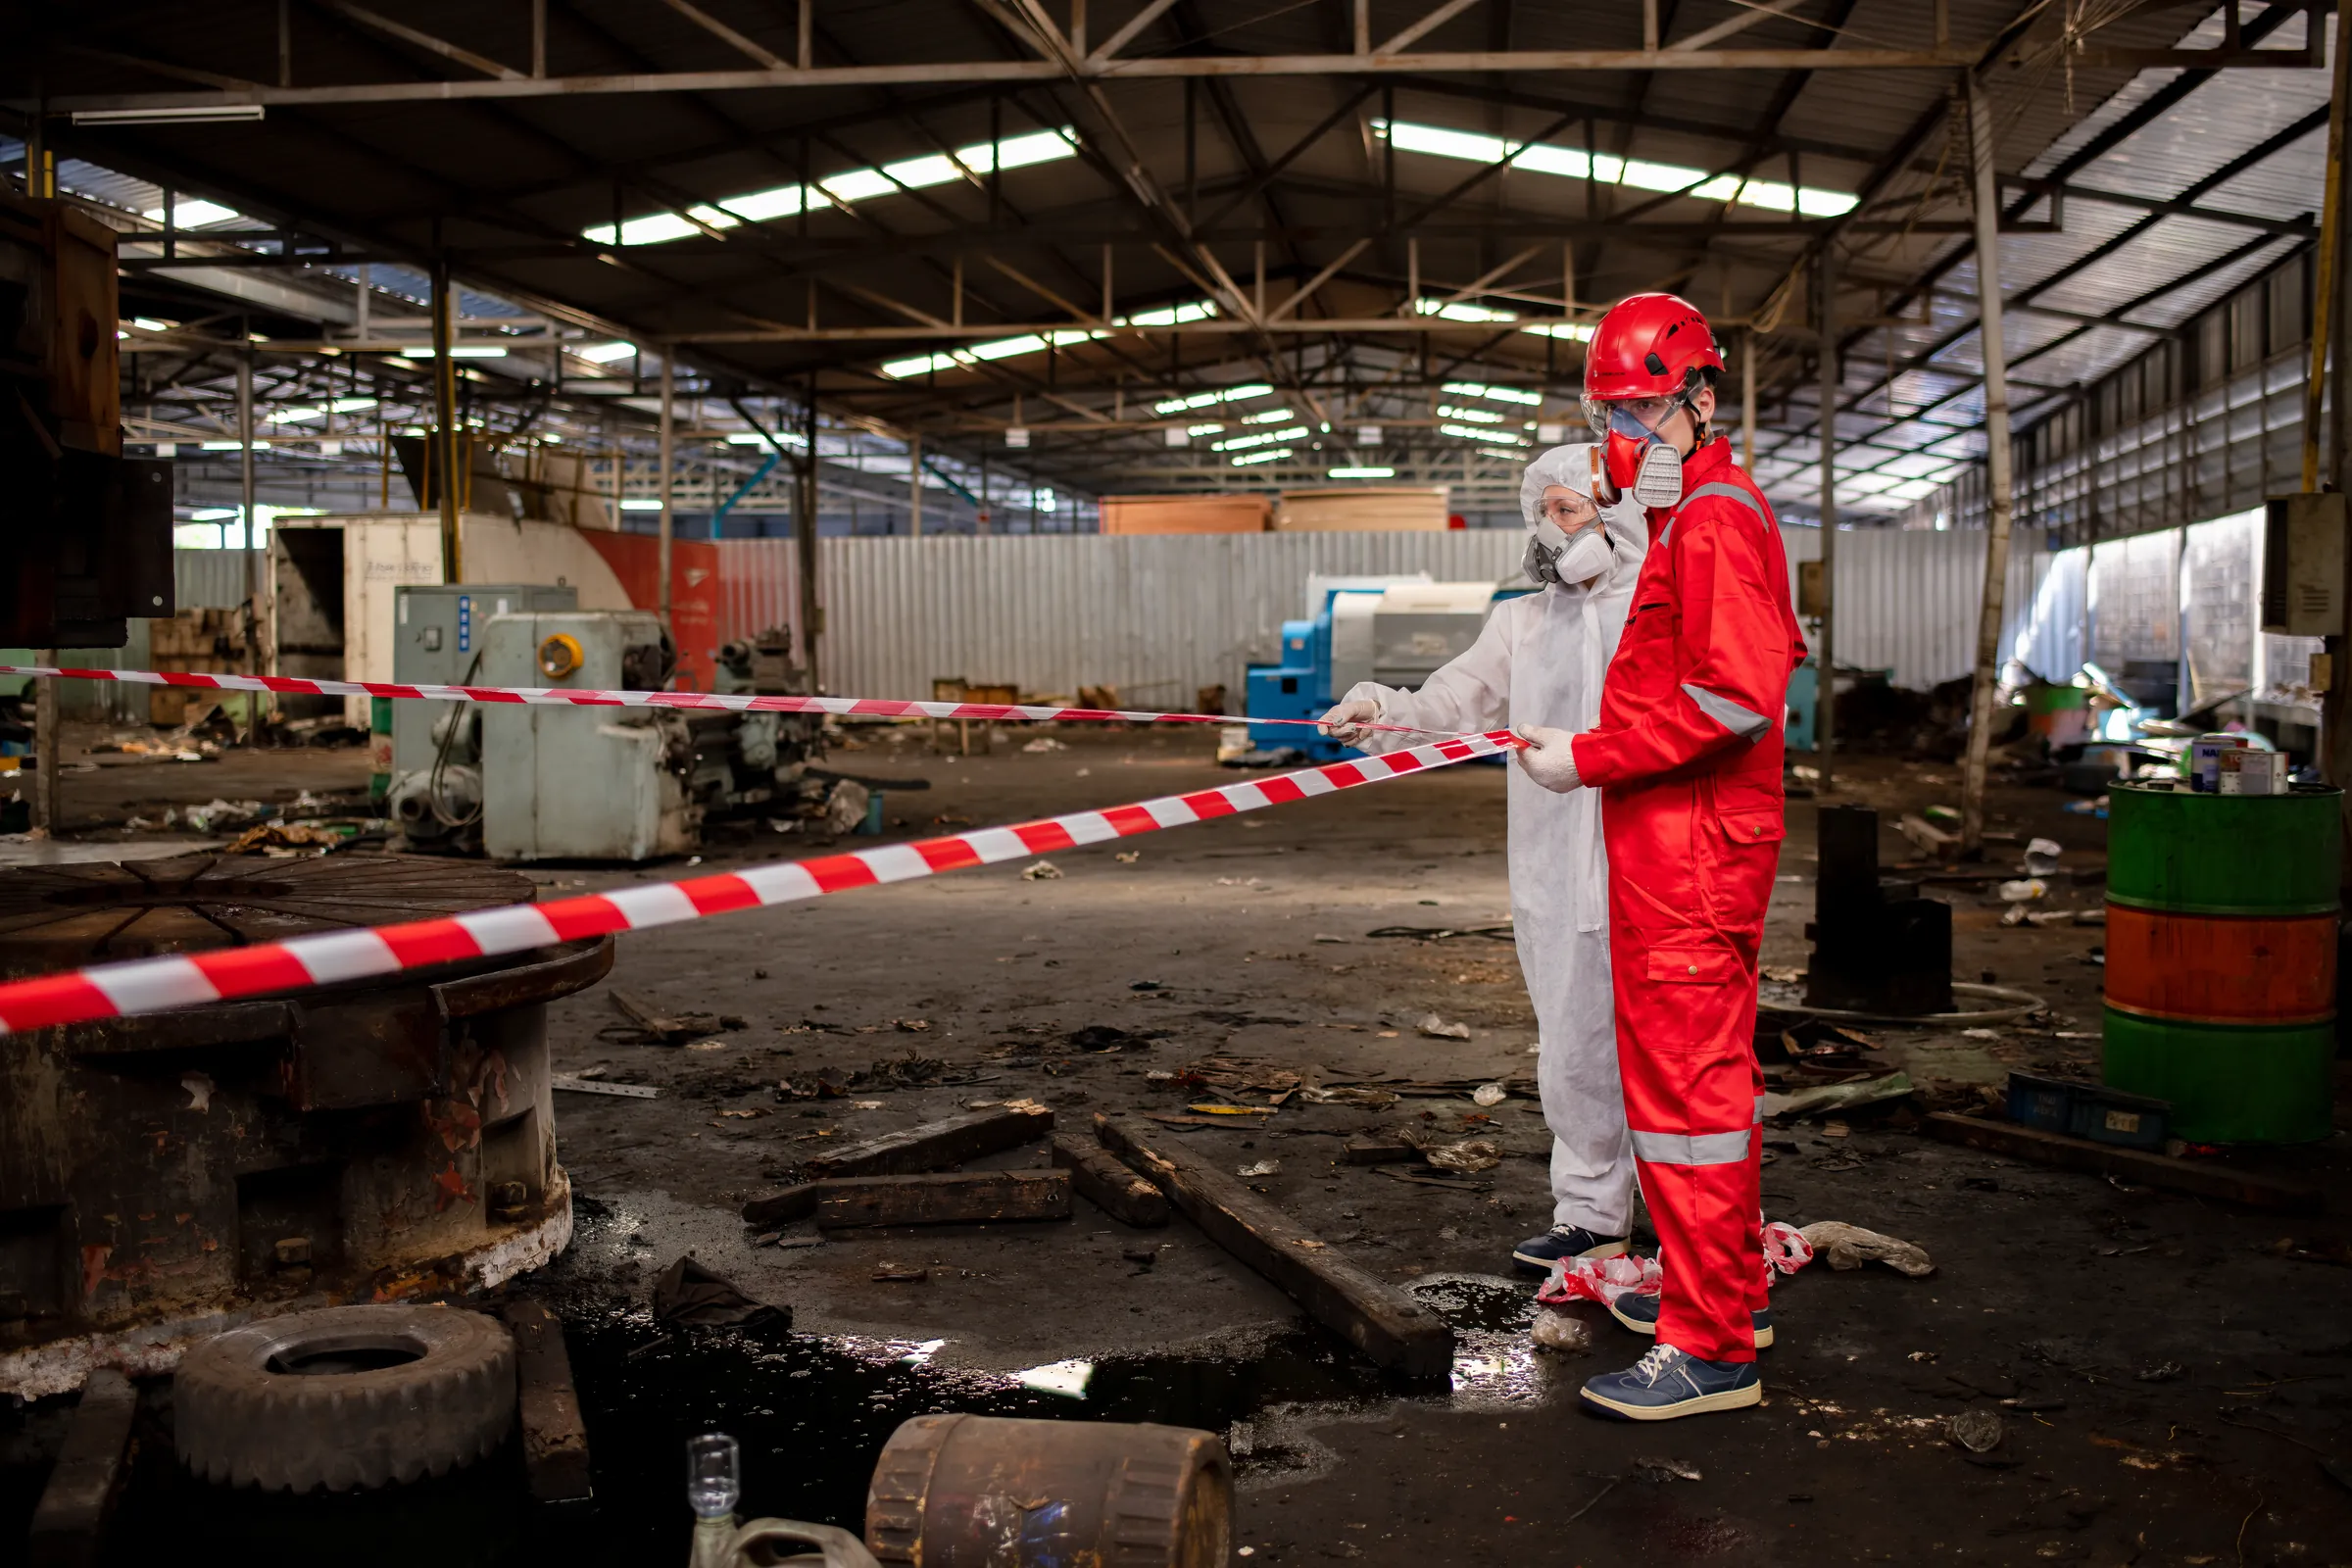
Business Interruption Insurance
Your property insurance rebuilds your building. Business Interruption insurance can help keep your business running while that happens. It can replace lost revenue, cover fixed costs and fund temporary relocation, so you can keep trading and hold your market position.
Lost profit and fixed costs while you cannot trade normally
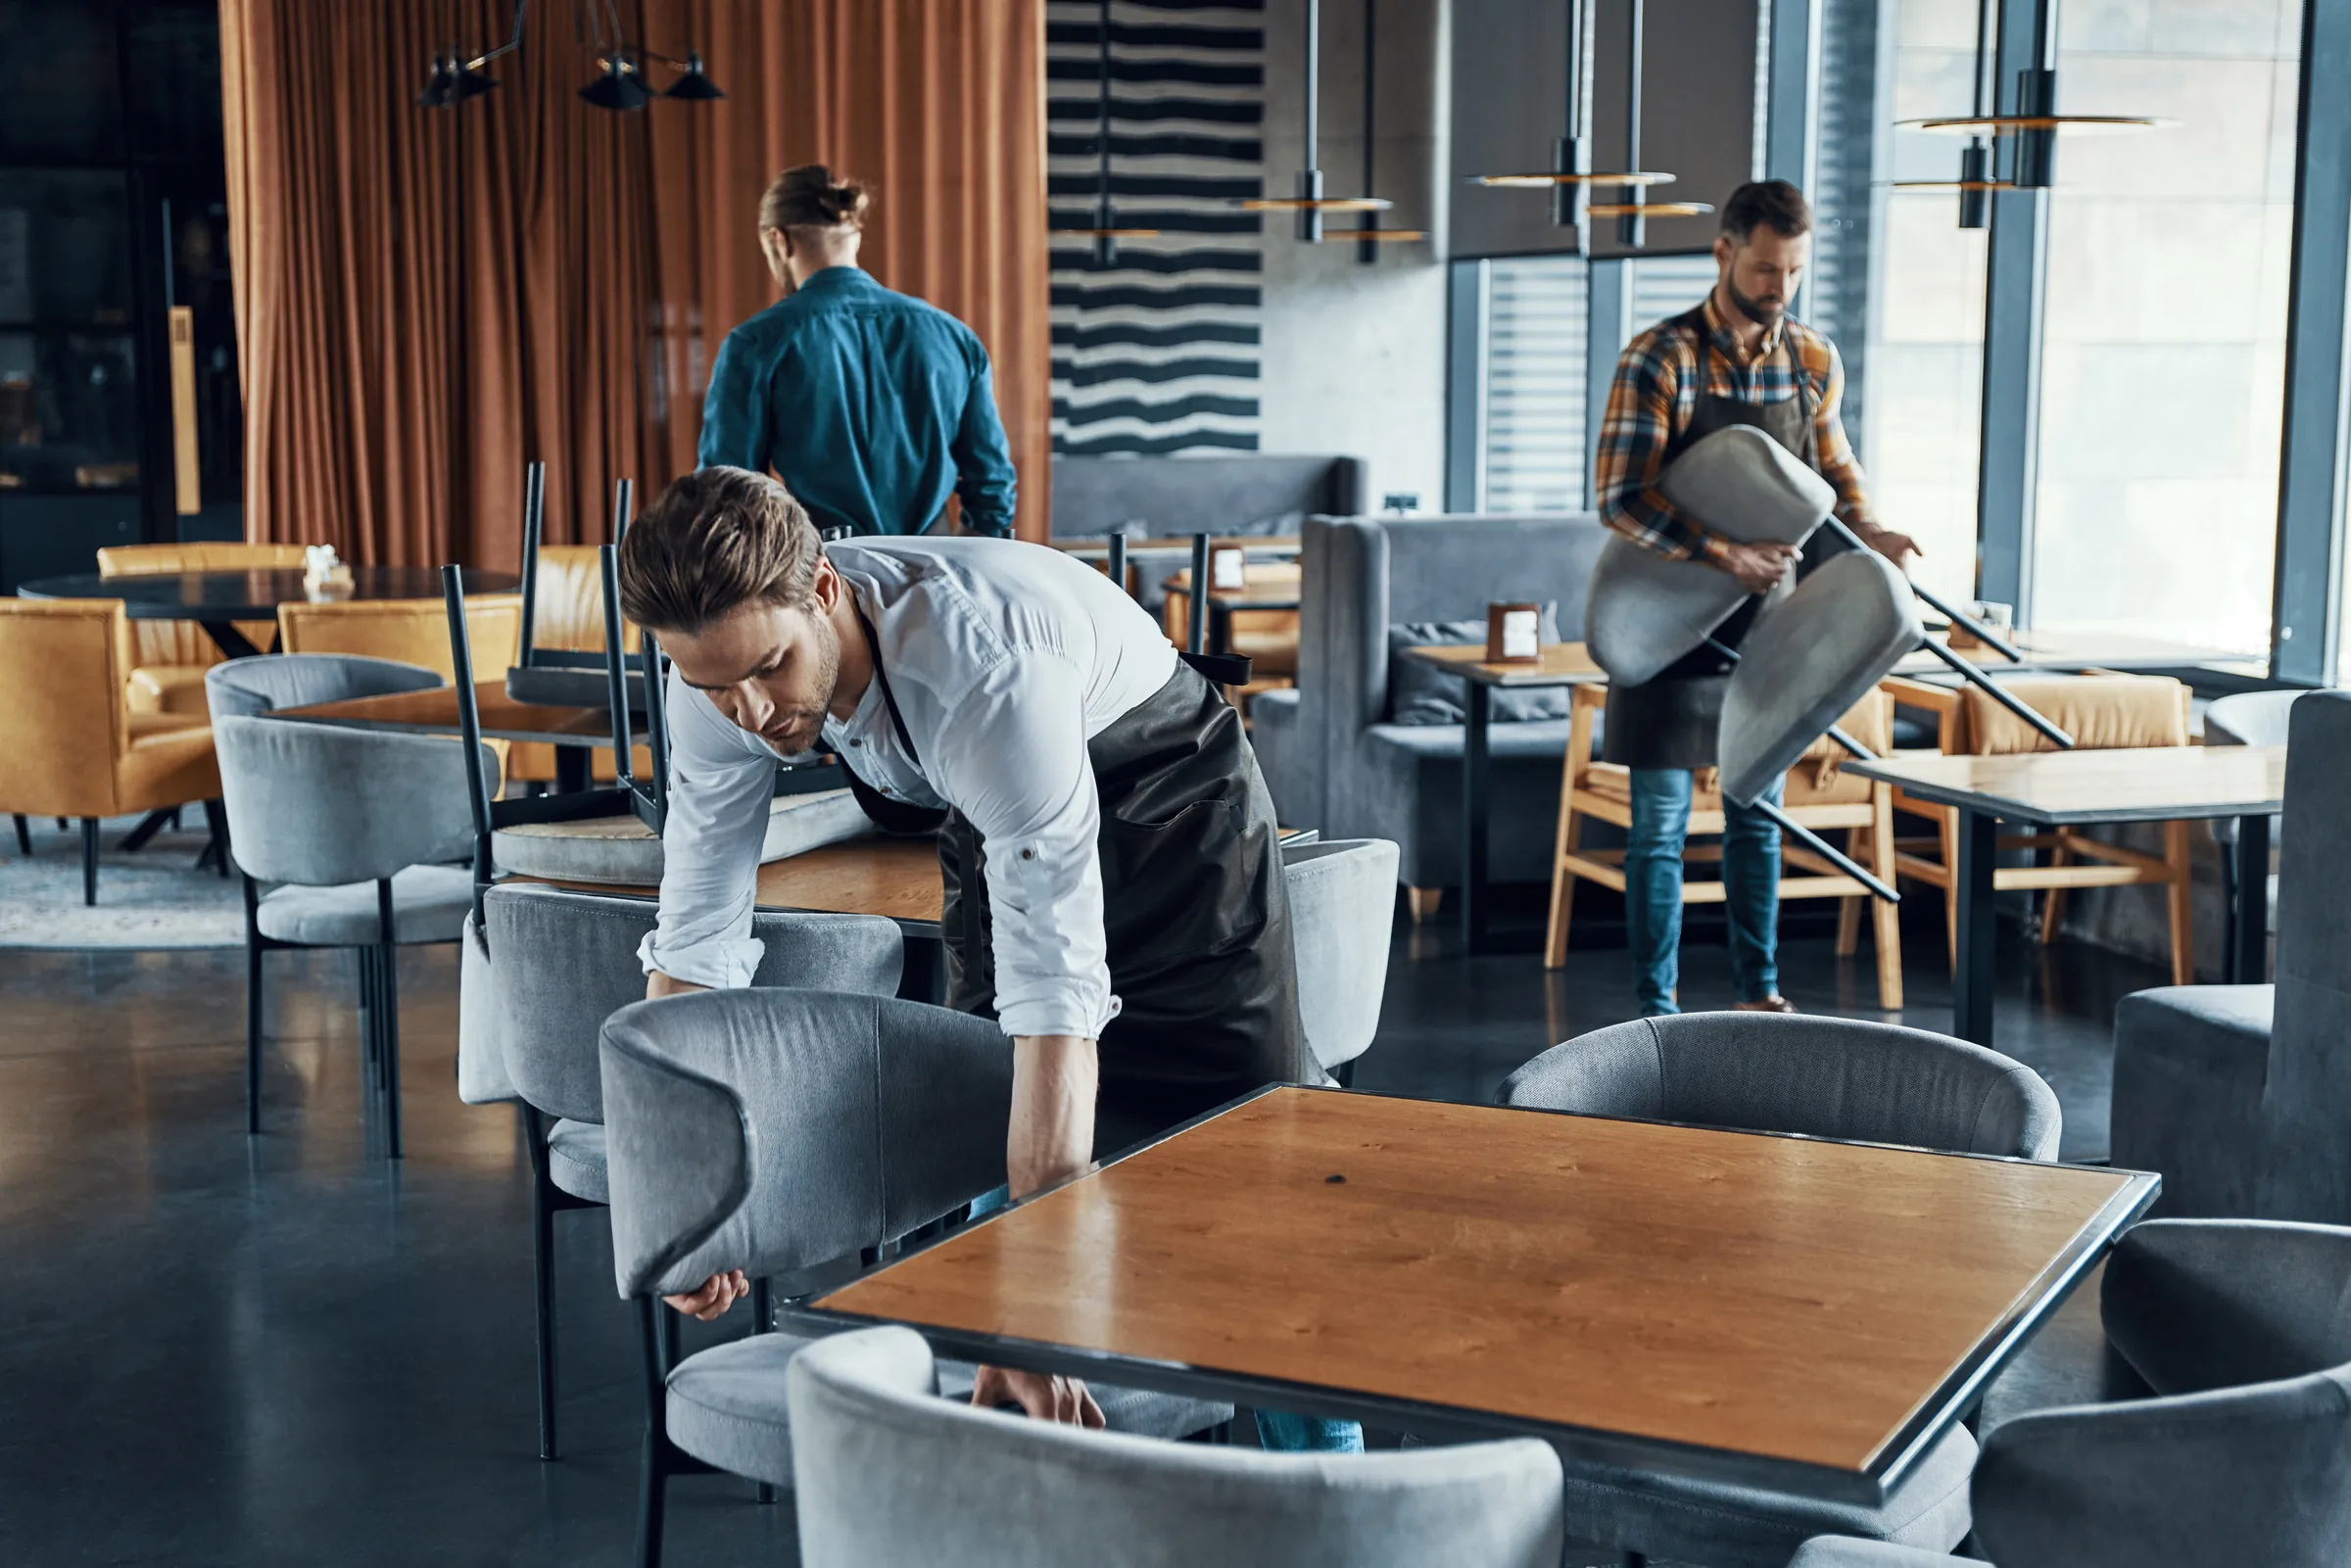
The building took ten weeks. The business took nine months.
An illustrative example of how Ardent can make the difference in a time of need.
A storm took the roof off a manufacturing site. The property claim was straightforward. The harder question was the indemnity period. It had been set at twelve months back when the business was half the size.
We had recalculated the indemnity period and the declared gross profit at the review before the loss. During the claim we built the loss of profits calculation with the client's accountant rather than leaving it to the insurer's forensic accountant.
The full loss of profits was met, including the increased cost of working while production ran from a leased site.
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
Our Business Interruption experts
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Mining, aviation, construction, retail and property
Steve has 40 years in insurance, most of it in construction and civil engineering, with underground mining, aviation, national retail and property development alongside. He is one of Ardent's founders, works from inside a client's business and keeps those relationships for the long term.
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
QPIB · Dip. Fin. Serv. (Ins Broking) · Dip. Integrated Risk Management · ANZIIF (Snr Assoc) CIP
Risk management and program design
Stephen co-founded Ardent and has 17 years in insurance, with clients from sole traders to multinational corporates. He works through the risks a business faces and helps decide what to avoid, reduce, retain or insure, balancing cover against cost. He has served on the committee of NIBA's NSW Mentoring Program.
What a client says about Ardent
Great service from Sarah and the team when it came to our insurance claim. Fast acting with the right people for the job and a great overall outcome.
Business Interruption FAQ
The indemnity period is the maximum duration for which BI will pay. It begins at the date of the insured event and runs until your business has recovered to its pre-loss trading position. Most businesses choose 12 or 24 months, but this should reflect your realistic reinstatement timeline. For complex buildings or specialised plant, rebuilding can take well over a year. Ardent assesses your reinstatement timeframe and recommends an indemnity period that covers your exposure. Choosing too short a period is one of the most common BI mistakes.
BI sum insured is typically based on annual gross profit (revenue minus variable costs) multiplied by your indemnity period factor. For example, if your annual gross profit is $2M and you have a 12-month indemnity period, you'd typically declare $2M. Many businesses understate their BI sum insured, either by not updating it as revenue grows or by using an incorrect definition of gross profit that excludes fixed costs. Ardent reviews your financials with you so the declared amount reflects your real exposure.
Standard BI requires physical damage to your property to trigger. If a nearby flood, fire, or gas leak makes your premises inaccessible without physically damaging them, standard BI may not respond. However, many policies offer a "Prevention of Access" extension that covers this scenario. Ardent reviews your premises location and business type and recommends appropriate extensions, particularly for businesses in flood-prone areas or near high-risk industrial sites.
Not under a standard BI policy. Supply chain disruption (where a key supplier's loss prevents you from operating) typically requires a "Dependent Properties" extension. For businesses that rely heavily on a single supplier or customer, this extension is important. Ardent maps your supply chain dependencies and advises on whether Dependent Properties cover is warranted for your risk profile.