Insurance for healthcare and allied health practices
Medical centres, dental practices, physiotherapists, psychologists and allied health clinics hold patient records, run expensive equipment and give advice that people act on. The cover has to protect the practice as well as the practitioner.
The practitioners, the records and the entity behind them
Professional Indemnity
Claims that treatment or advice caused harm or loss, for the practice entity and the staff who are not covered by their own indemnity.
Professional Indemnity coverCyber Insurance
Patient records are a target. Cover for breach response, notification under the Privacy Act, ransomware and the business interruption that follows.
Cyber coverManagement Liability
Employment claims, regulatory investigations and directors' liability for practice companies with partners, staff and locums.
Management Liability coverA practitioner's indemnity covers the practitioner, and stops there
Most practice claims land on the entity rather than the clinician, and the entity is often the one without cover.
Practitioner versus practice
Each practitioner's own indemnity covers that practitioner. It does not cover the company that employs them, the receptionist who gave the wrong instruction or the locum whose cover lapsed.
Equipment
Dental chairs, imaging equipment and sterilisers are expensive to replace and slow to source. Breakdown cover and the income lost while a room is out of action are separate from property cover.
Patient data
Health information is sensitive information under the Privacy Act. A breach means notifying patients and the regulator, and the policy has to fund both.
A practice management system held to ransom
An illustrative example of how Ardent can make the difference in a time of need.
Ransomware encrypted the practice management system at a multi-site clinic. Patient records were inaccessible and the notifiable data breach clock had started running.
We put the cyber policy's incident response provider on it immediately and dealt with the insurer while the practice dealt with patients. We also confirmed the entity was insured, not only the practitioners.
Records were restored and notification was made inside the statutory window. Response costs, legal advice and the income lost while clinics ran short were all covered.
Responds under Cyber Insurance
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
What insurers expect to see
Practice covers are rated on the services, the practitioner count and the records you hold. We go through them with you each year so new services and new staff are inside the policy.
- Every service offered, including telehealth and cosmetic procedures, declared to the insurer
- Practitioners, locums and contractors listed, with their own indemnity confirmed
- Equipment schedule at replacement value, with breakdown cover on the items that stop the practice
- Cyber limits sized to the number of patient records held
- Workers compensation and volunteer cover across every location
- Whether the entity needs its own medical malpractice cover, where the practice bills in its own name
Our Healthcare experts
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
QPIB · Dip. Fin. Serv. (Ins Broking) · Dip. Integrated Risk Management · ANZIIF (Snr Assoc) CIP
Risk management and program design
Stephen co-founded Ardent and has 17 years in insurance, with clients from sole traders to multinational corporates. He works through the risks a business faces and helps decide what to avoid, reduce, retain or insure, balancing cover against cost. He has served on the committee of NIBA's NSW Mentoring Program.
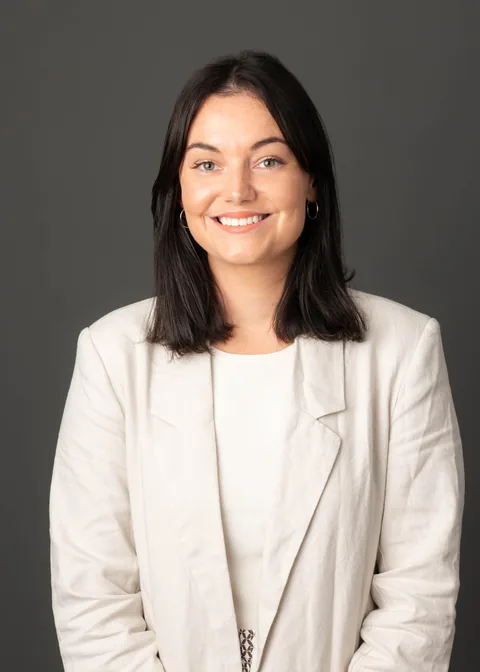
Mid-market businesses and jewellers
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
What a client says about Ardent
Read the full review on GoogleWe had a fantastic experience working with Sophie from Ardent Insurance. From our first conversation, she was incredibly knowledgeable, approachable, and genuinely committed to finding the right cover for our needs. Sophie took the time to understand our situation in detail and provided clear, tailored advice without any pressure.
She made what is often a confusing and time-consuming process feel straightforward and stress-free. Her communication was prompt and transparent, and we always felt confident that she had our best interests in mind.
We would highly recommend Sophie and the team at Ardent to anyone looking for reliable, professional, and personalised insurance support.