Insurance for not-for-profits and community organisations
Charities, associations, sporting clubs and community organisations run on volunteers, grants and the trust of the people they serve. The board carries personal liability, and the funding often depends on the certificate of currency.
The board, the community and the premises
Management Liability
Association liability: directors' and officers' cover for the board, employment claims and the cost of responding to a regulator or a funding body.
Management Liability coverPublic & Products Liability
Injury and property damage at events, on premises and in the community, including volunteers and the activities the organisation runs.
Liability coverProperty Insurance
Premises, contents, equipment and the vehicles the organisation owns, with the sum insured set to replacement cost rather than the value on the books.
Property coverVolunteers, funders and vulnerable people each need their own cover
Not-for-profit claims tend to fall on the people the standard policies were never written for.
Volunteers
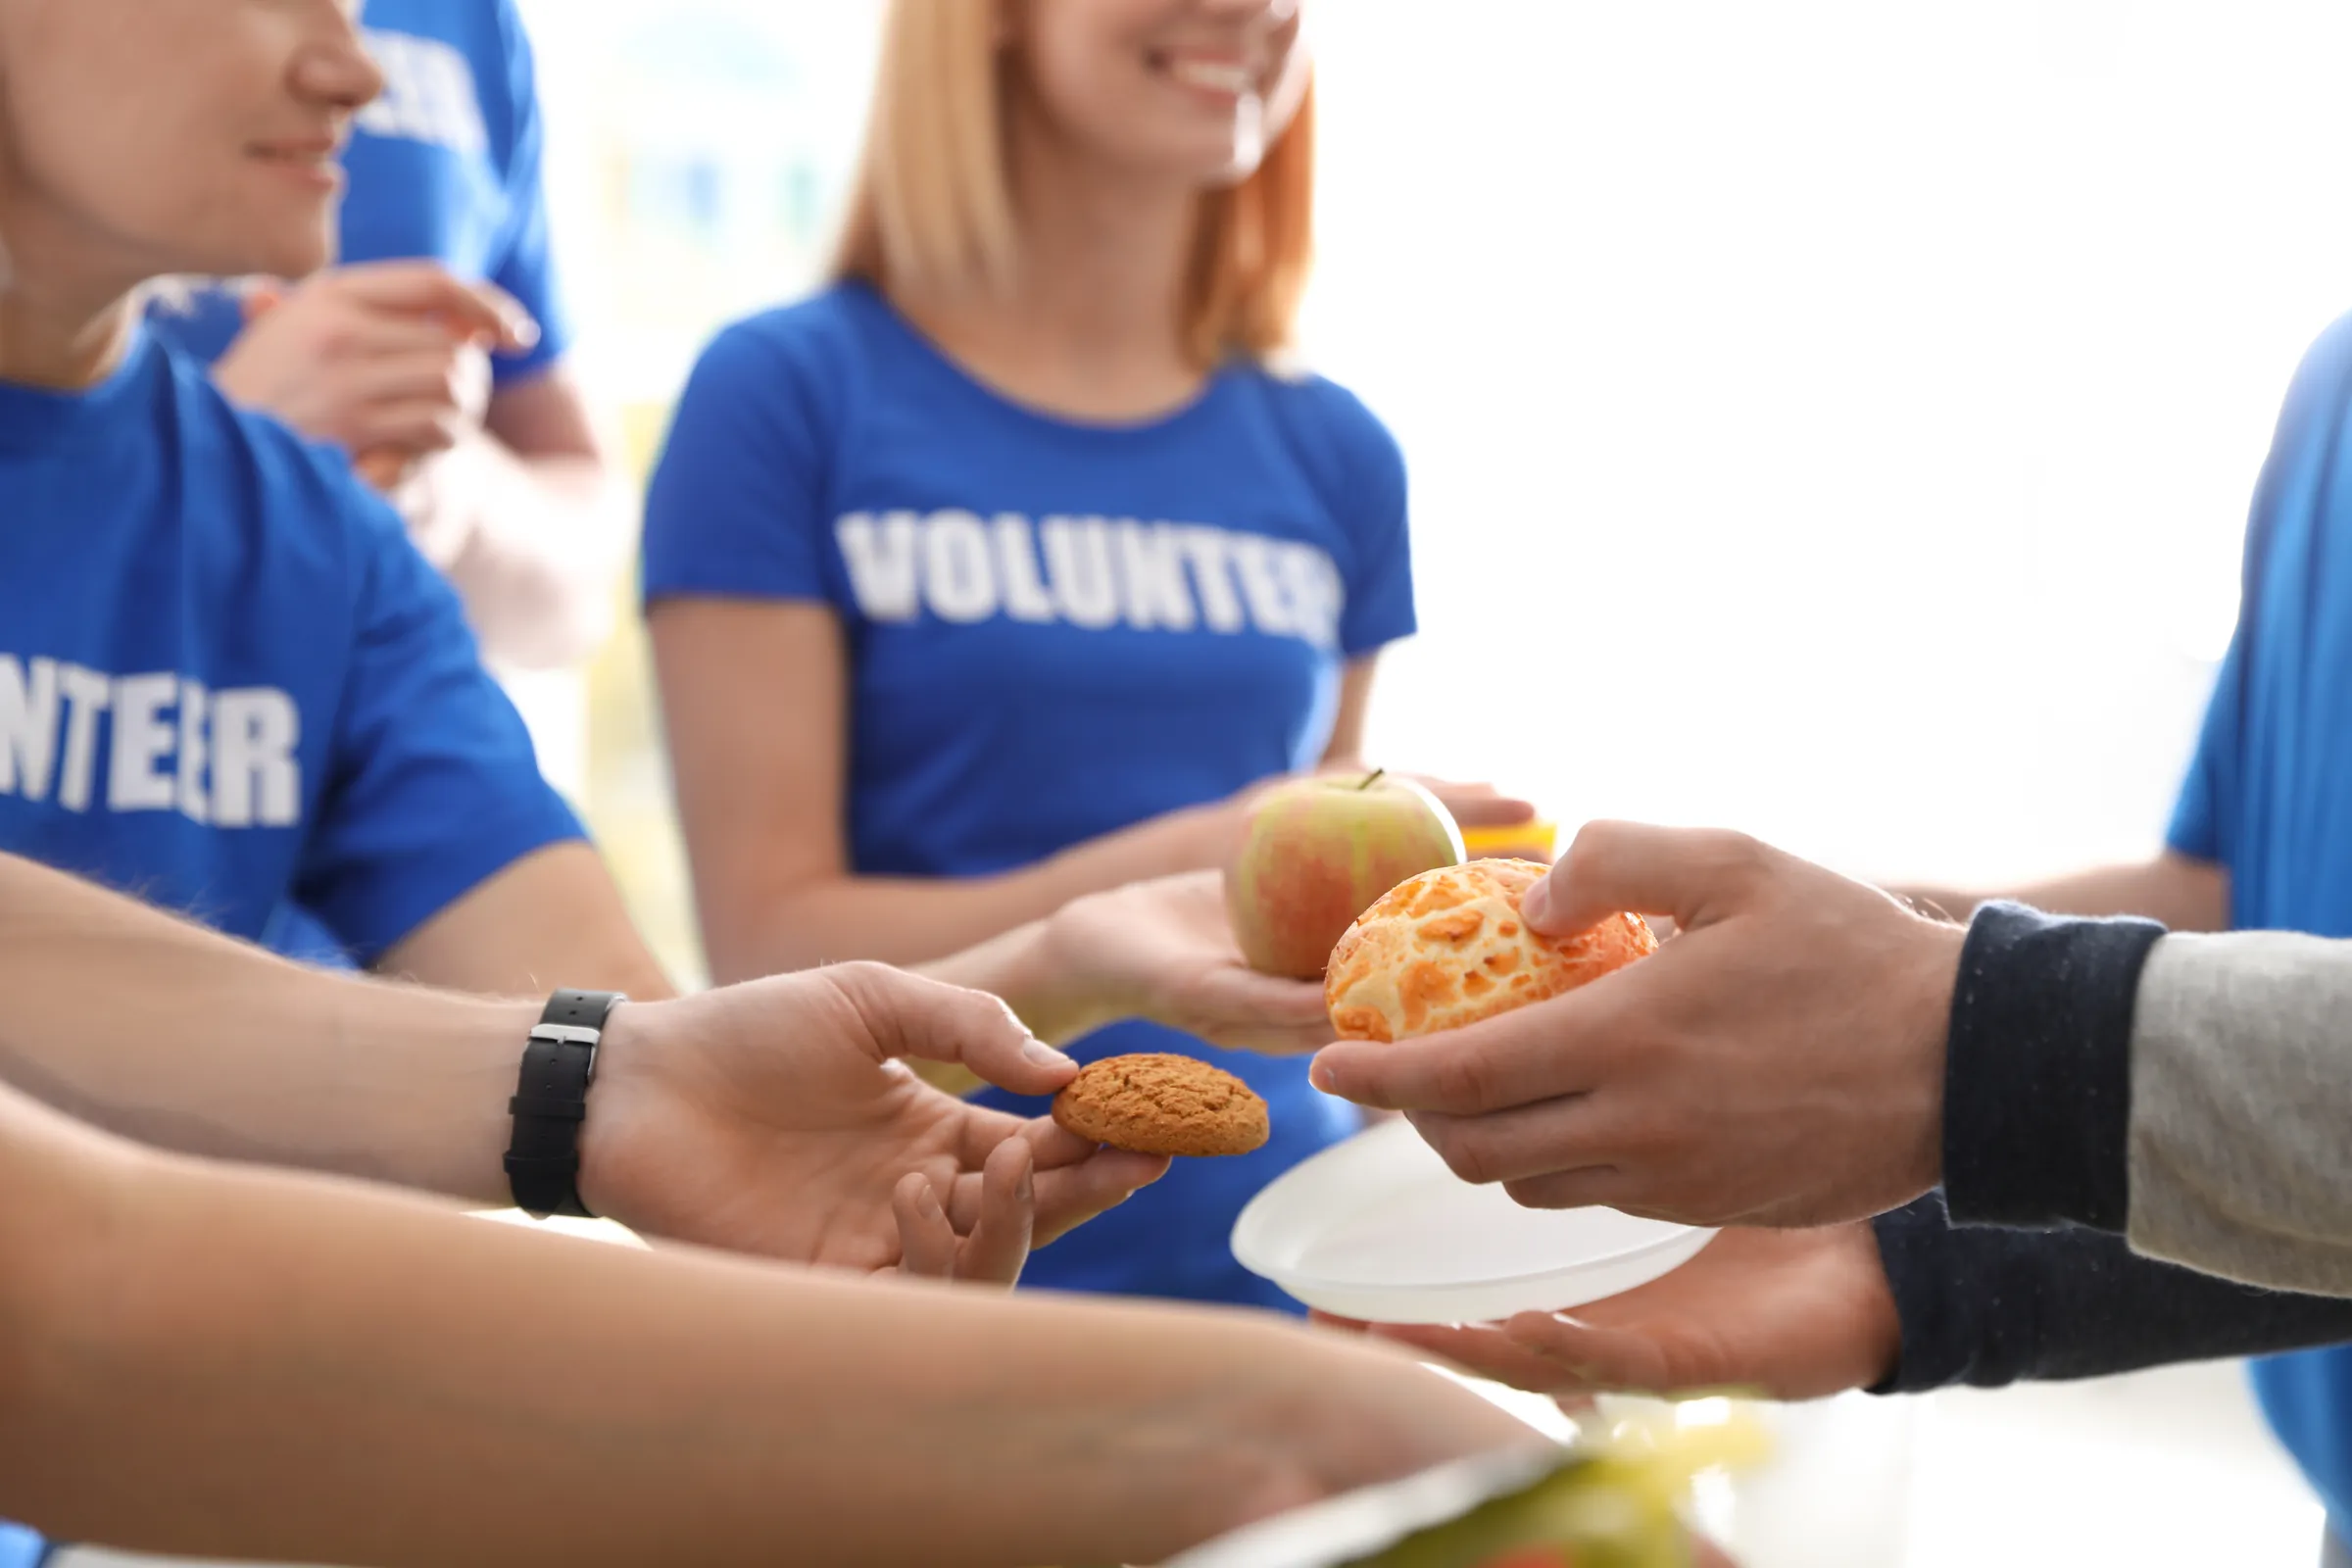
Volunteers are not employees, so workers compensation does not respond when they are injured. Voluntary workers personal accident cover is the policy that does.
Funding agreements
Government and philanthropic funders often set insurance requirements as a condition of the grant. A shortfall found at acquittal time can put the funding at risk.
Working with vulnerable people
Organisations that work with children, the elderly or people with disability face claims that ordinary liability policies exclude. Cover for those claims has to be arranged deliberately.
A volunteer injured at a community event
An illustrative example of how Ardent can make the difference in a time of need.
A volunteer was hurt setting up at a fundraising event. They were not an employee, so workers compensation did not answer, and the organisation had nothing to offer them.
The public liability policy had been extended to treat volunteers as employees, which we added after going through how the organisation actually runs its events.
The volunteer's claim was handled under the policy. The organisation was not left choosing between its people and its finances.
Responds under Public & Products Liability
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
What insurers expect to see
Not-for-profit covers are rated on the activities, the volunteers and the funding conditions. We go through them with you each year so the certificate of currency says what the funder needs to see.
- Association liability in place for every board and committee member
- Voluntary workers personal accident cover across every volunteer role
- Liability limits that meet each funding agreement and venue hire condition
- Activities declared to the insurer include events, fundraising and any work with vulnerable people
- Property and contents at replacement value, including donated equipment
- Cyber cover where you hold donor or client records
Our Not-for-Profit experts
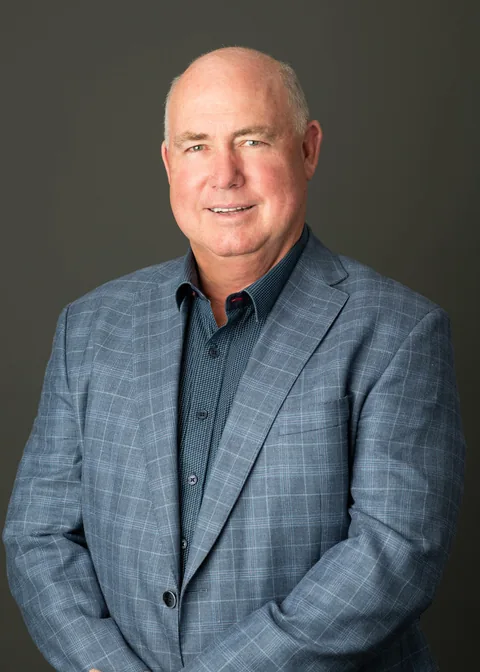
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Mining, aviation, construction, retail and property
Steve has 40 years in insurance, most of it in construction and civil engineering, with underground mining, aviation, national retail and property development alongside. He is one of Ardent's founders, works from inside a client's business and keeps those relationships for the long term.
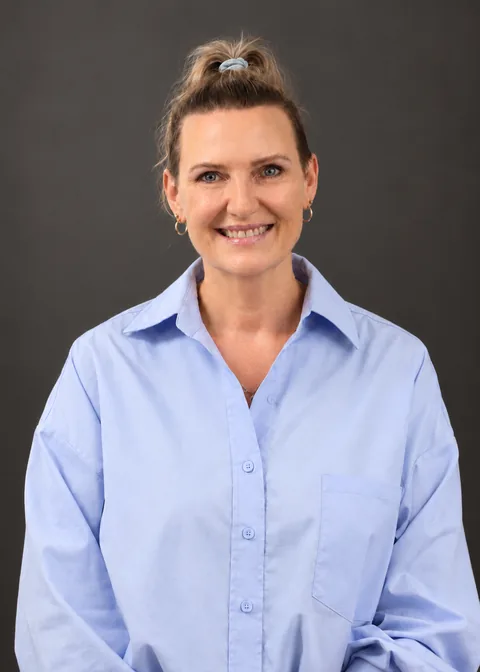
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
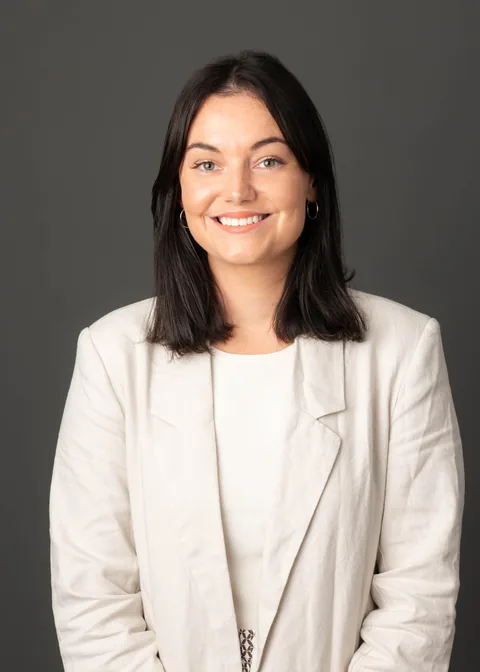
Mid-market businesses and jewellers
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
What a client says about Ardent
I found that the service at Ardent insurance very helpful and very polite customer service. A true pleasure to work with.