Prestige Home Insurance
Standard home and contents insurance is designed for average dwellings and average contents. It routinely falls short on prestige properties, extensive art collections, jewellery, and high-value possessions. Ardent places Prestige Home insurance through specialist underwriters who understand the complexity of insuring significant wealth.
Your home at an agreed value, and contents without sub-limits
Water that ran for weeks before anyone saw it
An illustrative example of how Ardent can make the difference in a time of need.
A concealed pipe failed behind a wall in a prestige residence. The water tracked under flooring through several rooms before it showed, and the joinery and stone were not standard items.
We had the home on an agreed value basis with the finishes properly scheduled, and appointed a building consultant for the client so the scope of works matched the original specification.
The repairs matched the original finishes rather than a builder's standard equivalent, and alternative accommodation was covered for the months the house was unliveable.
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
Our Prestige Home experts
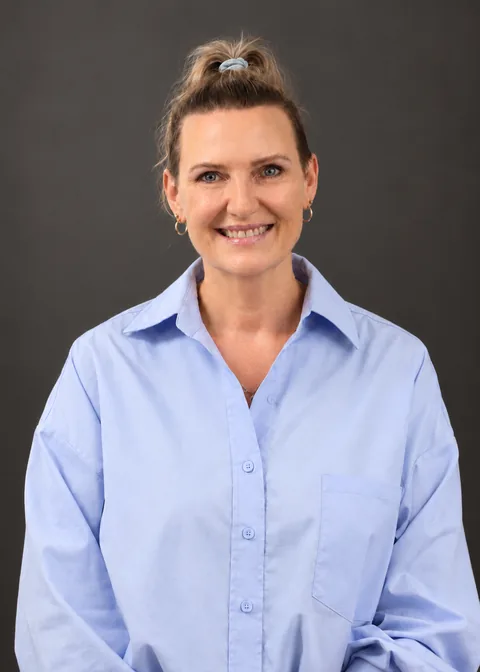
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
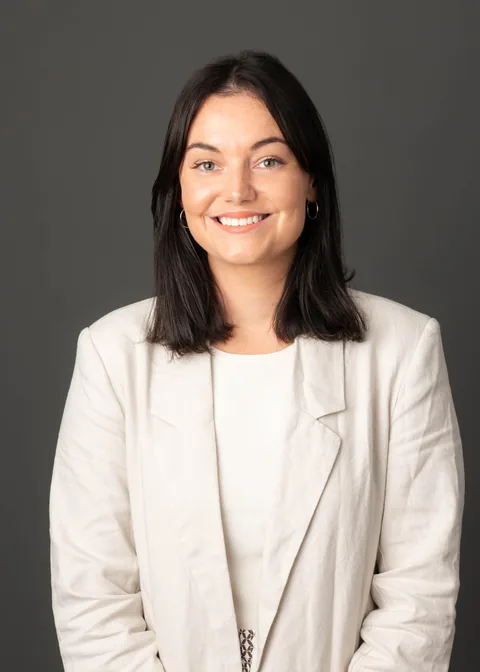
Mid-market businesses and jewellers
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
Cyber, property, motor fleet and technology
Kye has two and a half years in insurance broking, after working in retail management, and is studying for his diploma in insurance broking. He looks after a general book of clients, with a focus on cyber, property, motor fleet and technology. Clients find him thorough, efficient and understanding.
What a client says about Ardent
Sophie Hudson was a pleasure to deal with. Quickly and promptly acted to get my insurance sorted. Presented various options to choose from and very knowledgable. Highly recommend!
Prestige Home FAQ
Standard home and contents policies apply generic rebuild cost calculators, low sub-limits for valuables (typically $2,000 to $5,000 for jewellery), and exclusions for certain categories of property. For a prestige home, the rebuild cost calculated by an insurer's online tool can fall well short of the real cost to reinstate a custom home using quality materials and specialist trades. Standard policies also rarely cover fine art, collectibles, and wine collections at full value. Prestige Home policies use agreed values confirmed by independent valuers and generally have higher or fewer sub-limits, so you are less likely to be under-recovered after a loss.
Ardent recommends independent building and contents valuations for prestige properties, and can connect you with specialist valuers who understand high-value residential properties. We may receive a fee or commission for a referral, as our Financial Services Guide explains. Insurers can provide initial cover before valuations are complete, but formal valuations mean your agreed values stand up at claim time and remove the risk of under-insurance. Valuations are typically updated every 3 to 5 years to keep pace with rising construction costs and changes in collection values.
Yes. Specified valuables under a Prestige Home policy are typically covered on a worldwide basis, including while travelling. This includes theft, accidental loss (a watch left in a hotel, for example), and damage. Standard policies often restrict jewellery cover to the home and may explicitly exclude items being worn outside the property. Ardent checks that specified items have clear worldwide cover in the policy wording, and recommends declaring high-value items individually instead of grouping them under a contents limit, so you recover in full.
Yes. Prestige Home programs can cover multiple properties (a primary residence, a coastal holiday home, an investment property) under a single policy schedule. Each property is separately valued and insured, and the program can accommodate different occupancy conditions for each. Investment properties that are let commercially need specific occupancy terms noted, and Ardent applies the correct conditions so a claim arising during a tenancy isn't declined for occupancy misrepresentation.