Insurance for childcare and early learning centres
Long day care, preschools, family day care and outside school hours care run on approved places, ratios and the trust of parents. The cover has to hold up when a child is hurt in your care, and when the regulator asks how it happened.
The children, the educators and the approved provider behind them
Public & Products Liability
Injury to a child, a parent or a visitor, on your premises, on an excursion or at a centre event, and the legal costs that follow.
Public Liability coverManagement Liability
Employment claims from educators, and the cost of responding when the regulator investigates the approved provider or the nominated supervisor.
Management Liability coverProperty Insurance
Fit-out, playground equipment and the building where you own it, with the fees you lose while a room or a centre is closed.
Property coverThe abuse limit is rarely the limit on the schedule
Three things decide how a childcare claim runs, and none of them show up on a premium comparison.
Abuse liability
Cover for abuse claims often sits as a sub-limit under the liability section rather than at the full limit, depending on the insurer, on a claims-made trigger with its own retroactive date. Moving insurer can reset that date without anyone saying so.
The regulator arrives first
Under the National Quality Framework, a notifiable incident brings an assessment by the regulator before it brings a claim. Legal representation at that stage comes from management liability rather than public liability, and the two are often placed with different insurers.
Off the premises
Excursions, transport and incursions move children away from the address on the schedule. Some wordings limit cover to the approved service address unless the off-site activity has been declared.
A historical allegation, and the question of which policy year answered it
An illustrative example of how Ardent can make the difference in a time of need.
An allegation was made about conduct dating back several years. The service faced a regulatory notification and the prospect of a civil claim, and had changed insurer twice since the period in question.
We had preserved the retroactive date on the abuse liability section through both changes of insurer, and notified on the correct policy year with the history to support it.
Legal representation for the regulatory process and the civil defence were funded under the policy, and the service kept operating throughout.
Responds under Public & Products Liability
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
What insurers expect to see
Childcare covers are rated on approved places, ratios and what happens off the premises. We go through them with you each year so a new service or a new excursion is inside the policy before it runs.
- Approved places and current enrolment for each service you operate
- Working with children checks current for every educator, volunteer and student on site
- Abuse prevention policy and supervision plan, with the date each was last reviewed
- Playground equipment and soft fall inspected, with the reports kept
- Excursion and transport arrangements declared, including who drives and whose vehicle
- Incident register and any notifications made to the regulator in the past twelve months
Our Childcare experts
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
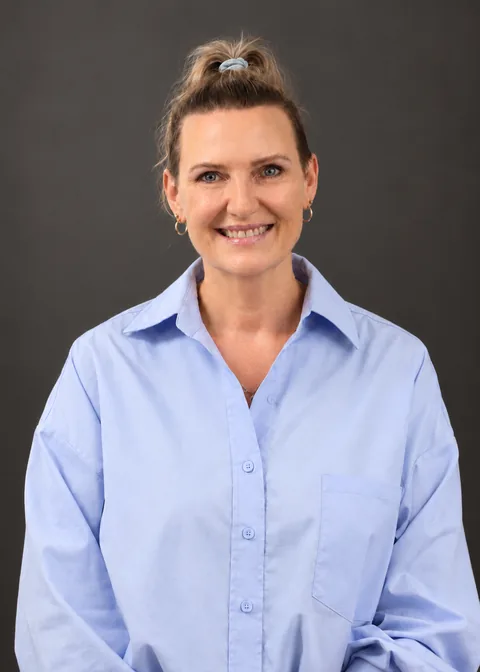
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
Mid-market businesses and jewellers
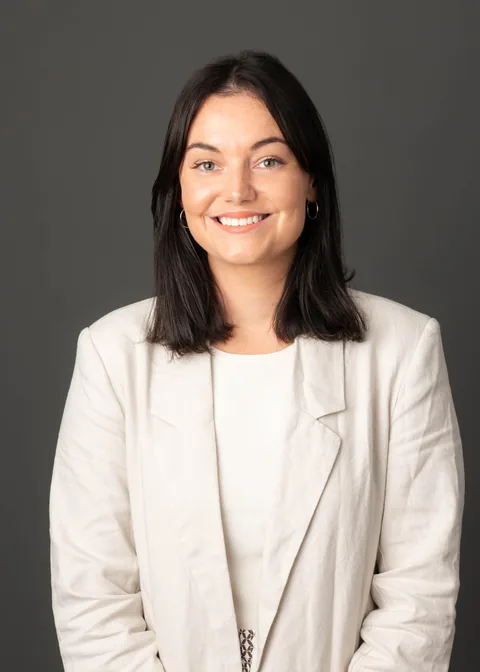
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
Cyber, property, motor fleet and technology
Kye has two and a half years in insurance broking, after working in retail management, and is studying for his diploma in insurance broking. He looks after a general book of clients, with a focus on cyber, property, motor fleet and technology. Clients find him thorough, efficient and understanding.
What a client says about Ardent
Sophie was a great help in setting up a new insurance policy for my small business. Friendly, efficient and very helpful in explaining all the finer details to ensure all went smoothly! Highly recommended - Thank you!