Insurance for strata schemes and owners corporations
Residential, commercial and mixed-use schemes, from a four lot block to a tower with a lift, a pool and a retail podium. The cover has to reinstate a building nobody owns outright, and stand behind the volunteers who run it.
The scheme, the building and the people who manage it
Residential Strata
Common property, office bearers liability and loss of rent for owners corporations, set against a valuation that still reinstates the building.
Residential Strata coverCommercial Strata
Retail, office, industrial and mixed-use schemes, where fit-out boundaries, GST and the length of the rent period all change the answer.
Commercial Strata coverProfessional Indemnity
For the strata management firm rather than the scheme. Claims that the management of a scheme fell short, from levy errors to maintenance obligations missed.
Professional Indemnity coverThe valuation is where most strata claims are decided
Three things settle how a strata claim runs, and none of them appear on a premium comparison.
The valuation is older than the build cost
A sum insured set three years ago against today's construction cost leaves the scheme funding the gap. Insurers apply average, and the shortfall lands on the owners as a special levy.
Nobody knows where the lot ends
The strata plan decides what is common property and what belongs to the owner. Fit-outs, upgrades and anything added since registration blur that line, and two insurers will point at each other while the owner waits.
The committee is personally in it
Office bearers are volunteers making decisions about other people's money. A levy struck wrongly or a repair deferred can become a claim against them by name.
A special levy that never had to be struck
An illustrative example of how Ardent can make the difference in a time of need.
Storm damage took the roof off a four storey block. The scheme's sum insured had been rolled over unchanged for several years while build costs moved, and the first assessment came back short of a full reinstatement.
We had commissioned a fresh replacement cost valuation at the previous renewal and had the sum insured lifted before the storm. At claim time we set out the reinstatement scope, including the compliance upgrades current code required, before the insurer's assessor formed a view.
The roof was reinstated to current code with no reduction for under-insurance. The owners corporation did not have to strike a special levy to cover a shortfall.
Responds under Residential Strata
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
What insurers expect to see
Strata covers are rated on the building, the plant in it and the claims the scheme has already had. We go through them with you each year so a works program or a change of use is inside the policy before it starts.
- A replacement cost valuation no more than three years old, with demolition, professional fees and escalation included
- The strata plan and any by-laws that change who insures what
- Common area plant listed: lifts, pumps, gates, air conditioning and fire systems, with service records
- Building works, defect rectification or fit-outs planned for the year, declared before they start
- Whether the scheme is registered for GST and can claim an input tax credit on a rebuild
- Claims history for the scheme, including water damage running between lots
Our Strata experts
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Mining, aviation, construction, retail and property
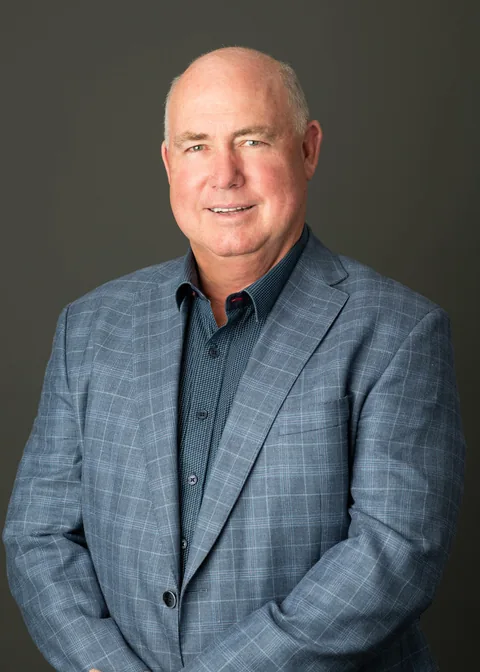
Steve has 40 years in insurance, most of it in construction and civil engineering, with underground mining, aviation, national retail and property development alongside. He is one of Ardent's founders, works from inside a client's business and keeps those relationships for the long term.
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Compliance, management and corporate clients
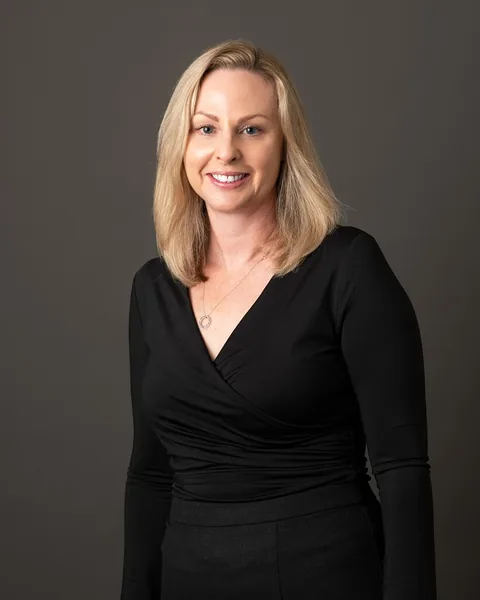
Eliza has worked across claims, personal insurance, small and medium businesses and corporate accounts. Before co-founding Ardent she managed a portfolio of ASX-listed companies, investment funds, and Lloyd's specialty and international placements. She now leads Ardent's compliance and management and still looks after her own clients, working as one of their team.
QPIB · Dip. Fin. Serv. (Ins Broking) · Dip. Integrated Risk Management · ANZIIF (Snr Assoc) CIP
Risk management and program design
Stephen co-founded Ardent and has 17 years in insurance, with clients from sole traders to multinational corporates. He works through the risks a business faces and helps decide what to avoid, reduce, retain or insure, balancing cover against cost. He has served on the committee of NIBA's NSW Mentoring Program.
What a client says about Ardent
Read the full review on GoogleEliza is beyond wonderful.
My apartment suffered water damage, leading to a long and complicated claim. Eliza acted as my broker, liaising with the insurer and coordinating everything.
From our very first conversation, she was warm and calm, while also clearly knowledgeable and organised. She kept me informed every step of the way and was always willing to answer my questions. When complications arose, Eliza went above and beyond to advocate on my behalf. She even took the time to discover details that I had completely overlooked, including an additional reimbursement I was entitled to. Her attention to detail was exceptional.
Although the claim went on for several months due to building complications, Eliza was always patient, proactive, and genuinely invested in helping me from beginning to end. She made what could have been an incredibly stressful experience so much easier to navigate. I always felt I was in truly capable hands.
I also spoke with a few members of Eliza's team while she was out of the office, and they were all friendly and helpful. This speaks volumes about the culture of the company.
I cannot speak highly enough of Eliza.
I will always be grateful for her wonderful support.