Insurance for pharmaceutical and life sciences businesses
Manufacturers, compounders, wholesalers and medical device businesses answer to the TGA, move stock that has to stay inside a temperature range, and carry a product's liability long after it leaves the dock.
The product, the cold chain and the freight between them
Public & Products Liability
Harm caused by a product you made, packed, relabelled or distributed. The limit has to hold for a whole batch, and for every market you supply into.
Public & Products Liability coverMachinery Breakdown
Cold rooms and controlled environment plant. Breakdown cover repairs the plant, and deterioration of stock is the extension that pays for what was sitting inside it.
Machinery Breakdown coverMarine Cargo
Active ingredients in, finished product out. A temperature-controlled clause, every storage point named and the carrier's limited liability all change what you recover.
Marine Cargo coverRecall costs sit outside the products liability limit
The covers that answer for a bad batch are bought separately from the one that answers for the harm it caused.
Recall
A products liability policy answers for the harm a product causes. Tracing the batch, pulling it back off the shelves and telling the market is a separate extension, with its own limit and its own triggers.
Cold chain
A temperature excursion spoils stock that still looks fine. Deterioration of stock has to be added to the machinery policy, and the cargo policy needs a temperature clause, or the loss stays with you.
Regulators and contracts
TGA conditions, GMP licences and recalls can draw investigation costs that a standard trade policy may not reach. Supply and contract manufacturing agreements decide who carries the liability, and they are usually signed before the broker sees them.
A temperature excursion in cold storage
An illustrative example of how Ardent can make the difference in a time of need.
A chiller controller failed overnight at a distribution site. The stock inside looked untouched, but the logger showed the batch had moved outside its licensed range, so none of it could be released.
Deterioration of stock had been added to the machinery breakdown policy at the last renewal, and the temperature logs were already sitting in the renewal file. We put the insurer's adjuster on site while the client handled the regulator.
The written-off stock and the failed plant were both met by the policy, along with the income lost while the site ran short. The controller was replaced under the same claim.
Responds under Machinery Breakdown
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
What insurers expect to see
These covers are rated on the product, the markets it reaches and the controls around it. We work through them with you each year, so a new line or a new export market is inside the policy before the first shipment.
- Product list and therapeutic goods classification declared, with any change of formulation
- Export markets named, since United States and European supply is rated on its own terms
- Recall limit tested against what it would cost to trace and replace your largest batch
- Cold chain protections listed: alarms, backup power, logging and a deterioration of stock extension
- Cargo policy carrying a temperature clause, with every storage and transit point named
- Contract manufacturing and distribution agreements read, so the liability each one hands you is insured
Our Pharmaceuticals experts
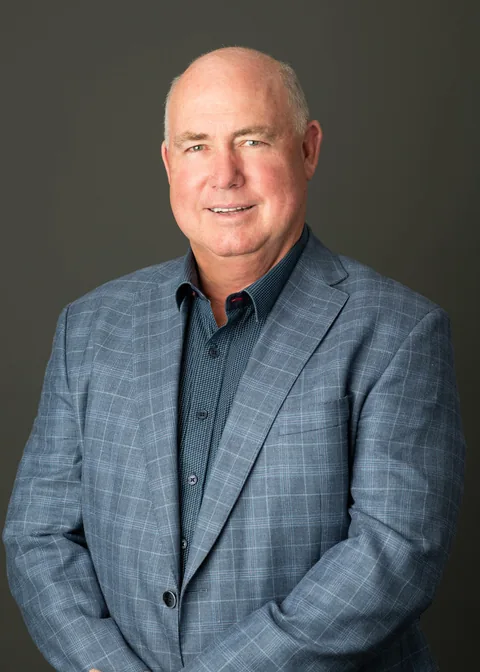
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Mining, aviation, construction, retail and property
Steve has 40 years in insurance, most of it in construction and civil engineering, with underground mining, aviation, national retail and property development alongside. He is one of Ardent's founders, works from inside a client's business and keeps those relationships for the long term.
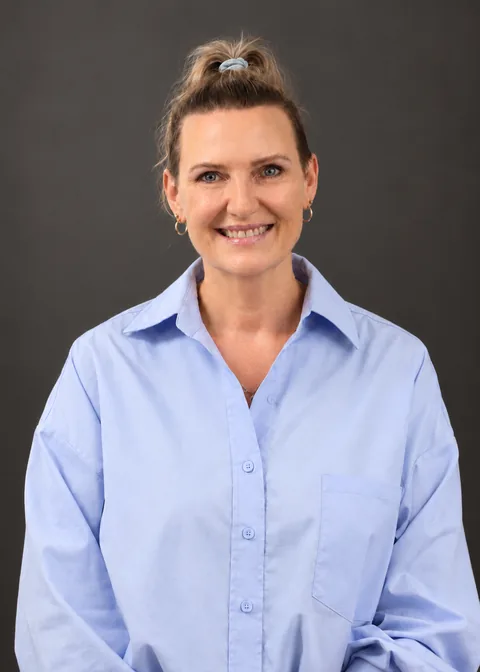
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
Mid-market businesses and jewellers
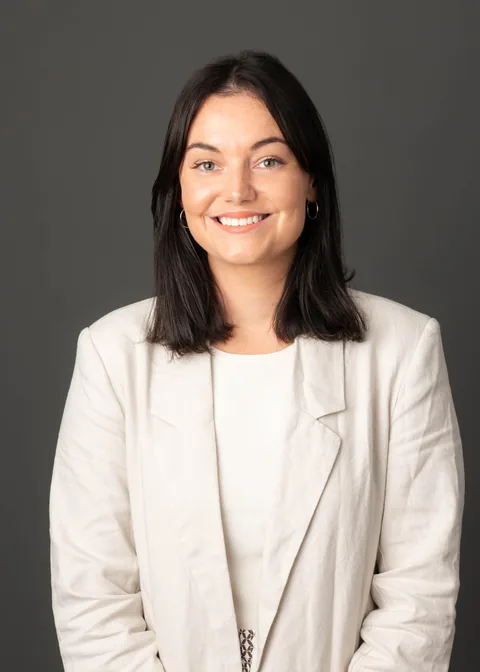
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
What a client says about Ardent
Read the full review on GoogleWe recently worked with Steve and Sophie at Ardent to secure our insurance cover, and the level of service was outstanding from start to finish.
They were professional, responsive, knowledgeable, and took the time to understand our business requirements to ensure we obtained the right coverage. What could have been a complex and stressful process was handled efficiently and with exceptional attention to detail.
Their communication throughout the process was excellent, and they consistently went above and beyond to achieve the best possible outcome for us.
It is rare to find service of this calibre these days. I would highly recommend them to any business or individual looking for an insurance broker who genuinely cares about their clients and delivers results.
Thank you for your exceptional support and professionalism.