Professional Indemnity Insurance
If your business provides advice, expertise or professional services, a client who believes your work caused them financial loss can sue, whether or not they are right. Professional Indemnity insurance can cover your defence costs and any compensation that follows, subject to the policy terms.
Defence costs and compensation for claims about your work
PI claims often have nothing to do with negligence. They come from misunderstandings, scope-of-work disputes, or a client looking for someone to blame after a commercial disappointment. The policy can respond whether or not you were at fault, subject to its terms.
A claim about advice given four years earlier
An illustrative example of how Ardent can make the difference in a time of need.
A client alleged that advice given several years before had cost them money. The firm had changed insurers twice in the meantime.
We had kept cover continuous with the retroactive date preserved through each change of insurer, and held the notification history to prove it.
The current insurer accepted the claim. Defence costs and the settlement were met, and the firm's retroactive cover stayed intact for the next renewal.
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
Our Professional Indemnity experts
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
QPIB · Dip. Fin. Serv. (Ins Broking) · Dip. Integrated Risk Management · ANZIIF (Snr Assoc) CIP
Risk management and program design
Stephen co-founded Ardent and has 17 years in insurance, with clients from sole traders to multinational corporates. He works through the risks a business faces and helps decide what to avoid, reduce, retain or insure, balancing cover against cost. He has served on the committee of NIBA's NSW Mentoring Program.
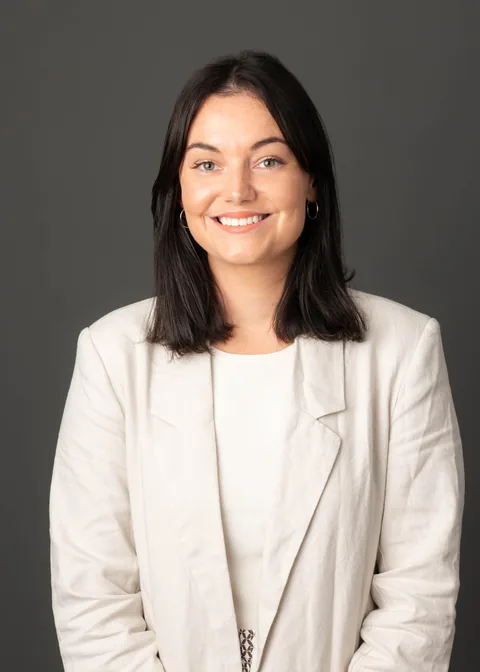
Mid-market businesses and jewellers
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
What a client says about Ardent
A thorough and extremely proficient team, compared to any past experiences, for our company PI and PL insurances. A pleasure to deal with.
With Ardent, I have full confidence in our insurance-cover, which has been challenging in the past, given our niche requirements.
Professional Indemnity FAQ
Any business that provides advice, expertise, or professional services for a fee should hold PI insurance. This includes: accountants, financial advisors, lawyers, architects, engineers, consultants, IT professionals, marketing agencies, real estate agents, surveyors, and many others. Some professions (financial advisors, lawyers, mortgage brokers) are required by law or by their professional body to hold PI. For others, clients or principal contractors may require it as a condition of engagement. Ardent advises on minimum limit requirements for your specific profession.
Professional Indemnity policies are "claims-made": they cover claims that are made (formally lodged) during the policy period, not when the alleged error occurred. This has two implications. First, you need continuous cover to protect against historical work. Second, you need a "retroactive date" going back to when you started providing professional services. Many businesses switch insurers without realising they have lost their retroactive date. We review your retroactive date at every renewal.
Limit requirements vary by profession, client contractual requirements, and the scale of projects you undertake. Some regulated professions specify minimum limits. Many government and corporate clients require minimum limits of $5M to $20M as a condition of engagement. Ardent benchmarks your limit against your largest single project value, your client contractual requirements and industry norms, then recommends a limit that matches your exposure.
It depends on how the policy is structured. If you've changed business names, restructured, or ceased trading under a previous entity, you may need "run-off" cover, a policy that continues to cover work performed under the old structure. Without run-off cover, a claim that emerges after you've ceased trading under that entity may have no policy to respond to. Ardent reviews your business history at inception and arranges cover for any prior entities, either under the current policy or through a dedicated run-off arrangement.