Residential Strata Insurance
Strata laws generally require an owners corporation to insure the building for what it would cost to rebuild, and that figure has to keep pace with construction costs. The requirements vary by state. Residential strata insurance covers the common property, the volunteers who run the scheme, and the rent or accommodation lost while repairs run.
The building, the committee and the owners behind them
A burst pipe on level six
An illustrative example of how Ardent can make the difference in a time of need.
A failed flexible hose in a top floor bathroom ran overnight. Water tracked down through four levels of lots and into the common lobby, and the repairs were going to take months with residents out of their homes.
We lodged under the strata policy and the affected owners' contents policies at the same time, so nobody sat waiting on someone else's insurer. We challenged the adjuster's scope where it cut the reinstatement short, and kept the committee and the owners updated through the repair.
Common property and the damaged lots were reinstated, and temporary accommodation was covered for the owners who had to move out. The scheme's excess was the only cost the owners corporation carried.
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
Our Residential Strata experts
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Mining, aviation, construction, retail and property
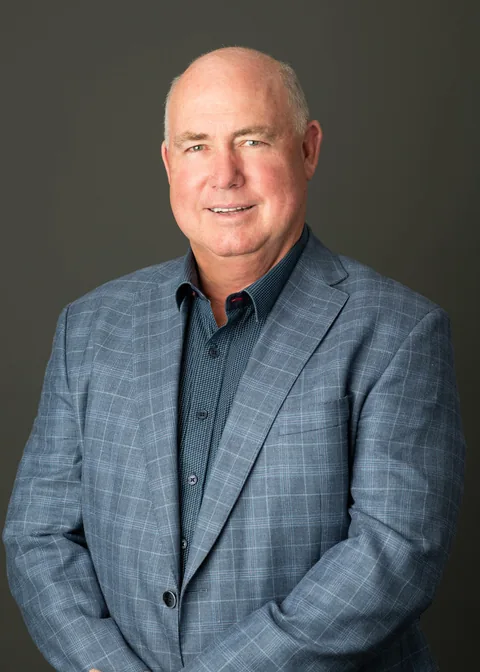
Steve has 40 years in insurance, most of it in construction and civil engineering, with underground mining, aviation, national retail and property development alongside. He is one of Ardent's founders, works from inside a client's business and keeps those relationships for the long term.
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Compliance, management and corporate clients
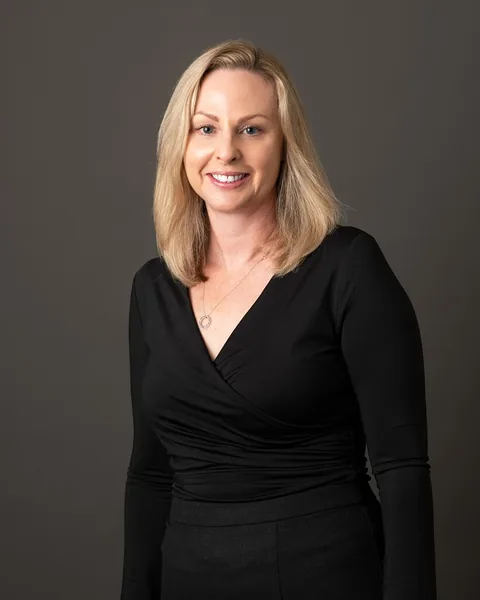
Eliza has worked across claims, personal insurance, small and medium businesses and corporate accounts. Before co-founding Ardent she managed a portfolio of ASX-listed companies, investment funds, and Lloyd's specialty and international placements. She now leads Ardent's compliance and management and still looks after her own clients, working as one of their team.
Mid-market businesses and jewellers
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
What a client says about Ardent
Read the full review on GoogleEliza is beyond wonderful.
My apartment suffered water damage, leading to a long and complicated claim. Eliza acted as my broker, liaising with the insurer and coordinating everything.
From our very first conversation, she was warm and calm, while also clearly knowledgeable and organised. She kept me informed every step of the way and was always willing to answer my questions. When complications arose, Eliza went above and beyond to advocate on my behalf. She even took the time to discover details that I had completely overlooked, including an additional reimbursement I was entitled to. Her attention to detail was exceptional.
Although the claim went on for several months due to building complications, Eliza was always patient, proactive, and genuinely invested in helping me from beginning to end. She made what could have been an incredibly stressful experience so much easier to navigate. I always felt I was in truly capable hands.
I also spoke with a few members of Eliza's team while she was out of the office, and they were all friendly and helpful. This speaks volumes about the culture of the company.
I cannot speak highly enough of Eliza.
I will always be grateful for her wonderful support.
Residential Strata FAQ
Generally no. The strata policy covers common property and, depending on the plan and the state, the original fixtures of each lot. Carpet, paint, blinds and anything an owner has added since are usually the lot owner's own contents cover. The boundary is set by the strata plan and the legislation rather than by the insurer, and it is worth knowing where yours falls before a claim rather than during one.
From a replacement cost valuation by a qualified valuer, covering demolition, professional fees, compliance upgrades and escalation during the rebuild. Market value is a different number and the wrong one to insure. Valuations date quickly when construction costs move, and an out-of-date figure is a common reason a strata claim settles short.
The committee's decisions. A levy struck incorrectly, a repair deferred, a by-law applied unevenly or a contractor engaged without proper process can each become a claim against the individuals who made the call. The cover can fund their defence and any award, subject to the policy terms, so volunteers are not left personally exposed for running the scheme.