Jewellers Block Insurance
Jewellery businesses face risks that general property and contents policies were never written for: robbery, mysterious disappearance, customer goods liability and a showcase smash-and-grab. Jewellers Block is a policy designed for the trade, and Ardent places it through specialist underwriters who understand the exposures jewellers face every day.
Your stock and your customers' pieces, on the premises and in transit
A ram raid, and the stock that was not the jeweller's own
An illustrative example of how Ardent can make the difference in a time of need.
A retail store was rammed after hours and the window cabinets cleared. Part of the loss was memo stock held on approval from suppliers, and part was customers' pieces left in for repair.
The policy carried separate limits for goods held on approval and customers' goods, set after we went through how stock actually moves through the business at the review.
Own stock, memo stock and customers' goods were all paid. The supplier relationships held because the memo stock was settled quickly.
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
Our Jewellers Block experts
QPIB · Dip. Fin. Serv. (Ins Broking)
Client relationships and team leadership
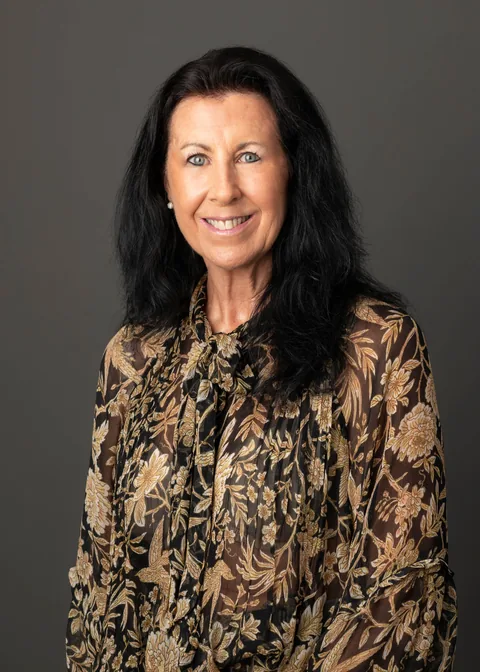
Lynne co-founded Ardent after 45 years in insurance broking, and strong client relationships have run through all of it. In recent years she has worked as a General Manager, bringing general broking experience together with managing a team. At Ardent she supports the staff and keeps the workplace positive, which clients feel in every dealing they have with us.
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
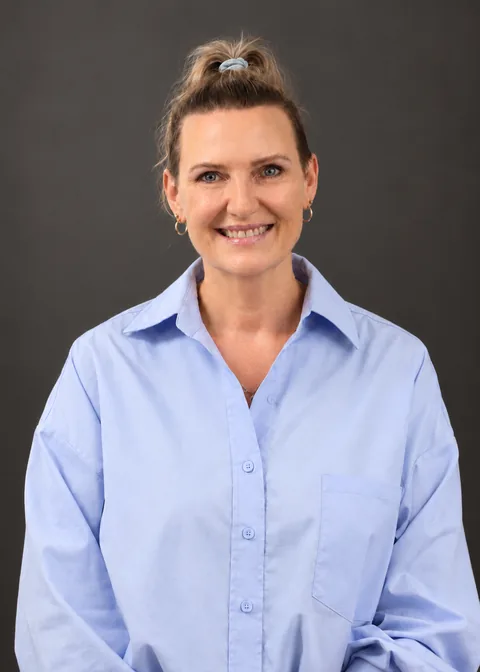
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
Mid-market businesses and jewellers
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
What a client says about Ardent
Read the full review on GoogleSophie H was exceptional in helping me secure insurance for my jewellery business.
She was incredibly patient with my many questions and took the time to understand how my business operates.
I've been working with Sophie for a couple of years now, and no matter how my business has evolved, she has always adapted and adjusted the insurance to suit. Every question I've had, she's found a solution for, and her support has genuinely contributed to the growth and confidence of my business.
Couldn't be happier with the service. Highly recommend.
Jewellers Block FAQ
Jewellers Block is a specialist insurance product designed for businesses in the jewellery trade: retailers, manufacturers, repairers, valuers and wholesalers. Standard commercial property and contents policies were never designed for the exposures of a jewellery business. They typically apply very low sub-limits for jewellery and cash (often $5,000 to $20,000), exclude mysterious disappearance, exclude goods held in trust for customers, and impose restrictive security conditions that are impractical for a working jewellery store. Jewellers Block policies are written to cover the values jewellers hold and the ways losses occur in the trade.
Yes. Mysterious disappearance is a key benefit of Jewellers Block that standard policies exclude. In jewellery retailing, stock can go missing without a clear cause: a piece removed from a showcase that doesn't return, a discrepancy found during stocktake, or an item that cannot be located despite no apparent theft. Many standard policies require evidence of theft (forced entry, a known thief, a witnessed theft) before they will pay a claim. Jewellers Block policies typically cover mysterious disappearance within agreed limits, recognising this as an inherent risk in the trade. Ardent checks that your policy wording explicitly covers this exposure and that the limits are realistic for your stock values.
Jewellers Block insurers typically require monitored alarms, secure display cases, out-of-hours security (safes or security rooms for overnight storage), and sometimes specific safe ratings for higher-value operations. These requirements are negotiated at placement and documented in the policy, so you know exactly what you need to maintain for cover to respond. Ardent works with you so the security conditions are achievable for your premises and operation. Conditions that cannot practically be met are a common source of claim disputes, and we work to prevent that at the start.
Cover for goods away from your principal premises (markets, trunk shows, trade fairs or client meetings) can be structured into your Jewellers Block policy. This typically requires declaration of the specific events or a blanket cover for temporary locations, with sub-limits applying to the value taken off-premises at any one time. Ardent checks that your policy covers the locations and formats in which you trade, including any specific conditions (security, storage overnight) that apply at temporary locations.