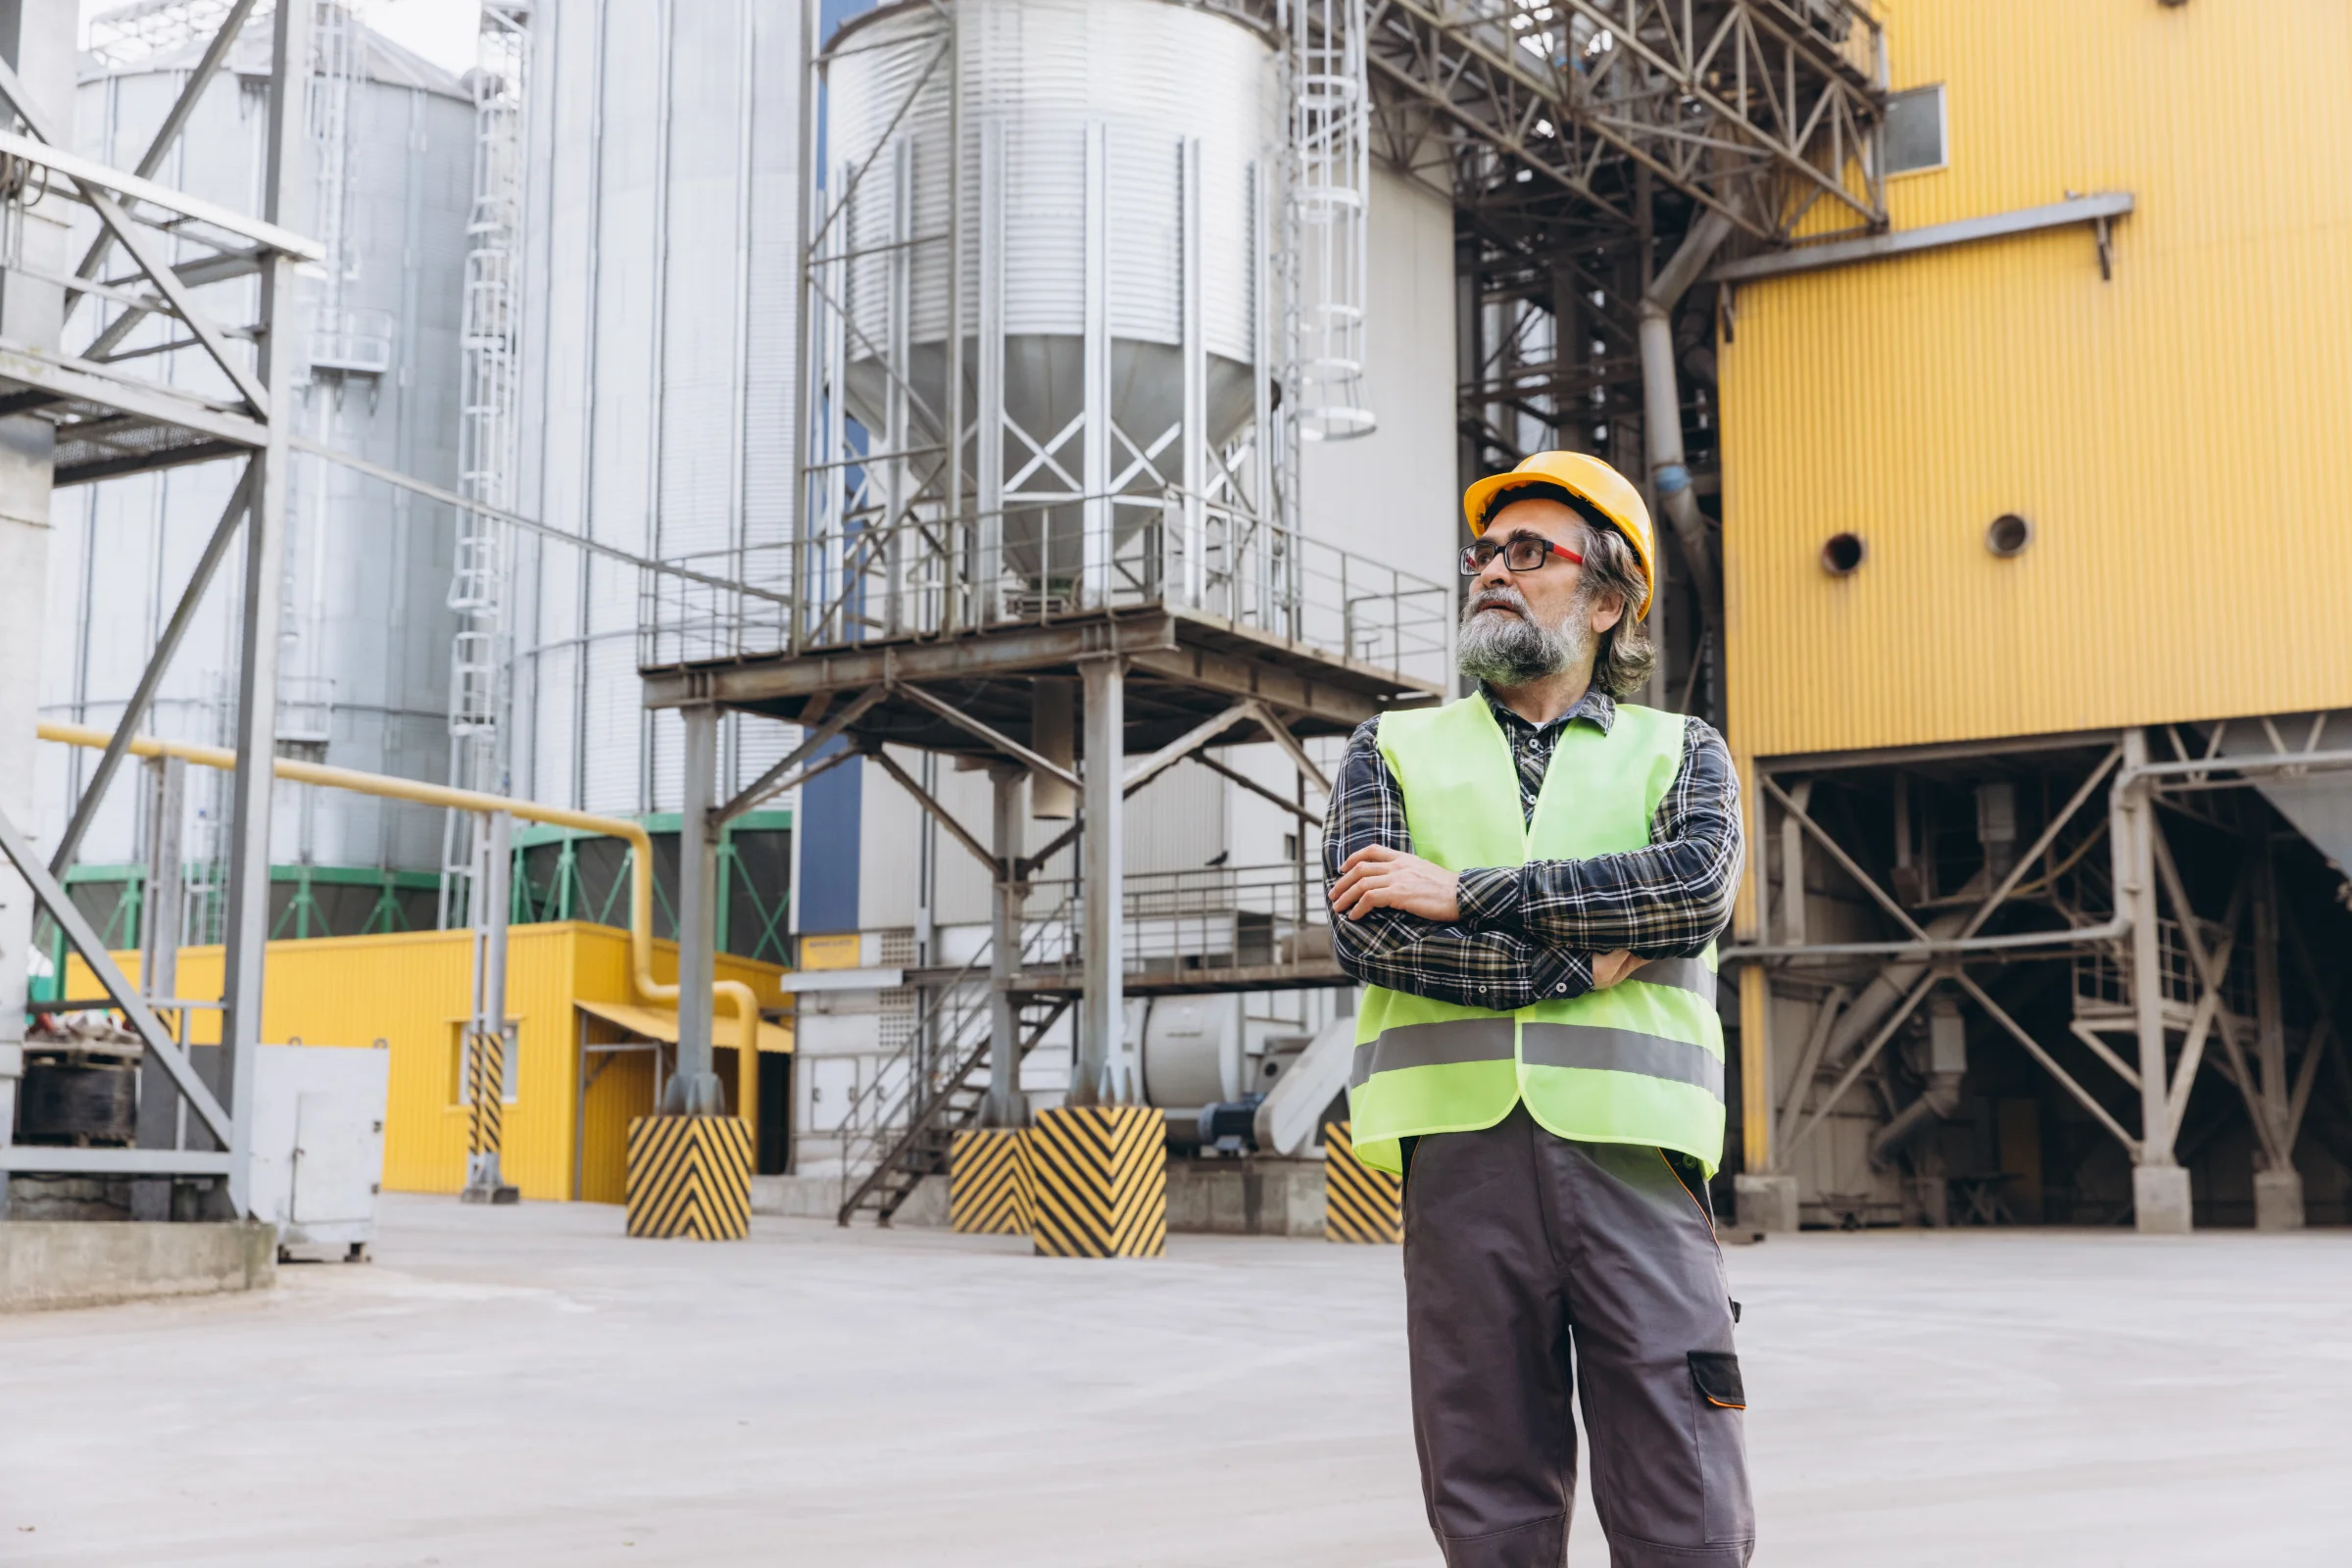
Property Insurance for Australian businesses
Protect your commercial buildings, contents, stock and plant, with a sum insured that reflects what it would cost to rebuild today. Construction costs have risen sharply, and underinsurance is one of the most common and costly mistakes Australian businesses make.
Cover for buildings, contents, stock and plant
A well-structured property policy reflects your true exposure: replacement cost accuracy, and the business interruption tail that follows any major loss.
Why replacement cost accuracy matters
Most businesses set their sum insured once and forget it. Construction costs have risen sharply since then, and many Australian businesses are now underinsured without knowing it.
Sum insured audit
We benchmark your declared values against current building cost indexes, identify any shortfall, and document the basis of valuation so it holds up at claim time.
Wording review
Not all property policies are equal. We review the fine print, especially flood, storm surge, business interruption linkage and claims conditions, so you know exactly what you have.
Claims advocacy
When a property loss occurs, we manage the claim alongside you: liaising with loss adjusters, challenging under-settlements, and pushing to get your business trading again as quickly as possible.
BI integration
Property damage is only part of the cost. We structure Business Interruption cover alongside property policies so revenue lost during reinstatement is covered too.
A warehouse fire, and a sum insured that had not kept up
An illustrative example of how Ardent can make the difference in a time of need.
Fire spread from a neighbouring tenancy and took a distribution warehouse and most of the racking with it. The building sum insured had been rolled over at the same figure for three years while construction costs moved.
We had flagged the shortfall at the previous renewal and the sums insured were lifted before the loss. When the claim was lodged we set out the reinstatement scope ourselves before the insurer's assessor attended.
The rebuild settled on a reinstatement basis with no reduction for under-insurance. The client traded from a temporary site while the building went back up.
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
Our Property Insurance experts
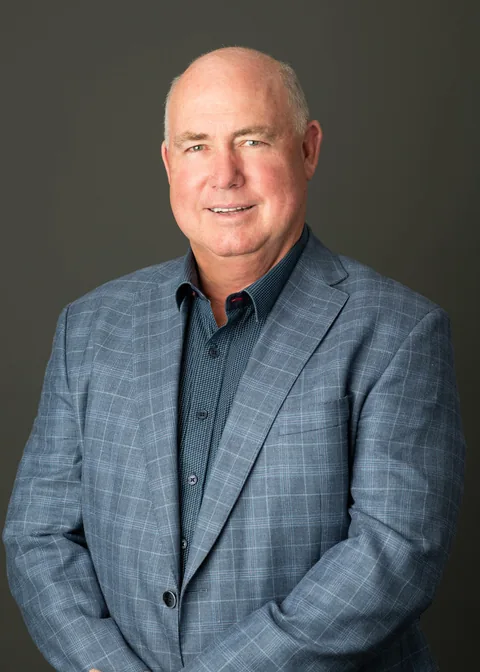
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Mining, aviation, construction, retail and property
Steve has 40 years in insurance, most of it in construction and civil engineering, with underground mining, aviation, national retail and property development alongside. He is one of Ardent's founders, works from inside a client's business and keeps those relationships for the long term.
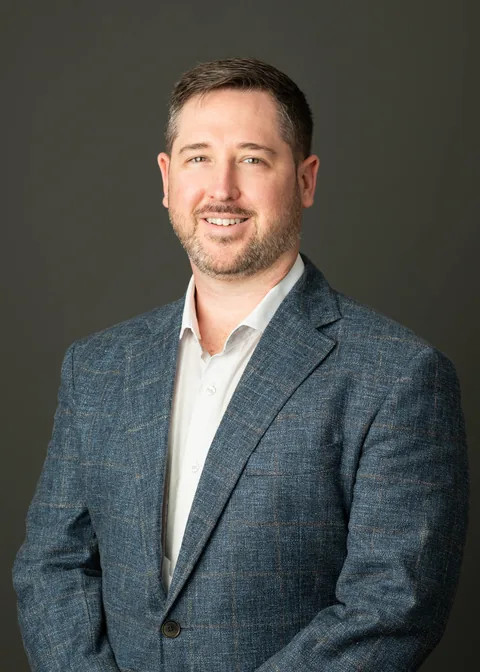
QPIB · Dip. Fin. Serv. (Ins Broking) · Dip. Integrated Risk Management · ANZIIF (Snr Assoc) CIP
Risk management and program design
Stephen co-founded Ardent and has 17 years in insurance, with clients from sole traders to multinational corporates. He works through the risks a business faces and helps decide what to avoid, reduce, retain or insure, balancing cover against cost. He has served on the committee of NIBA's NSW Mentoring Program.
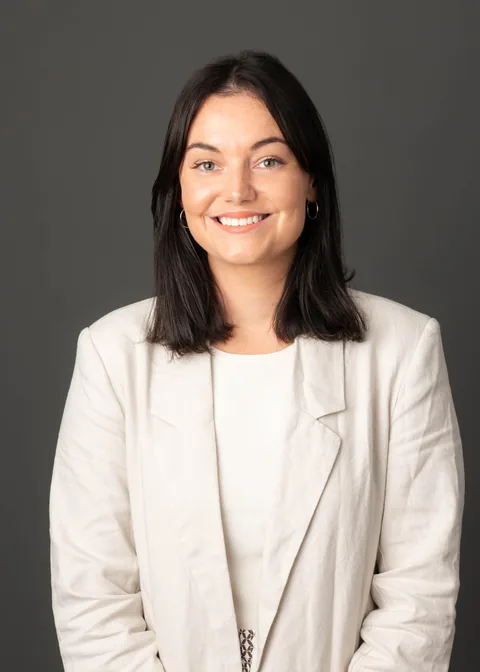
Mid-market businesses and jewellers
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
What a client says about Ardent
Steve and Sophie are very professional and have done a great job in finding the best insurance policy for us. They always arrange for meeting to explain the policy inclusions and make recommendations on best options . We highly recommend them. Thanks Ardent!
Property Insurance FAQ
Market value is what you could sell the property for today. It reflects land value, location and demand. Replacement cost is what it would cost to rebuild or replace the structure to its current specification. For insurance purposes, replacement cost is generally the right basis. Market value is typically lower and leaves you short if you need to rebuild. Ardent benchmarks your sum insured against current construction cost indices to check it is accurate.
Not necessarily. Storm damage is usually covered under standard commercial property policies, but flood cover varies significantly between insurers and policy wordings. Some policies exclude flood entirely; others offer it as an optional extension. The definition of flood versus storm water runoff also matters a great deal when a claim arises. Ardent reviews the flood risk at your location and checks that your policy wording covers the flood events most likely to affect your premises.
Underinsurance occurs when your declared sum insured is less than the actual cost to rebuild or replace. With Australian construction costs rising significantly since 2020, a property insured on a five-year-old valuation may now be well underinsured. Signs you may be underinsured include sums insured that have not been updated in three or more years, leaving fit-out costs, professional fees or demolition costs out of your calculation, or insuring for market value instead of replacement cost. Ardent conducts a sum insured audit at no cost to new and existing clients.
Not automatically. Property insurance replaces your physical assets. Business Interruption (BI) insurance replaces the revenue you lose while those assets are being repaired or replaced. BI cover is a separate extension, and one of the most misunderstood products available. Without it, a property claim that shuts down your operations for six months could still be financially devastating, even with a full property settlement. Ardent structures BI alongside your property program so the two fit together correctly.
Insurers typically impose minimum security requirements: monitored alarm systems, deadbolt locks, window locks and sometimes CCTV. These conditions are usually listed in your policy schedule and must be complied with at all times for claims to be covered. Failing to maintain agreed security measures can void theft or malicious damage claims entirely. Ardent advises clients on what requirements apply to their specific policy and helps document compliance as part of the renewal process.
Yes. Tenants typically need to insure their fit-out, contents, and stock regardless of whether they own the building. Some leases also require tenants to insure the building itself or maintain glass cover. Ardent reviews your lease obligations as part of structuring your property program, so you satisfy both your insurer's requirements and your landlord's contractual conditions.