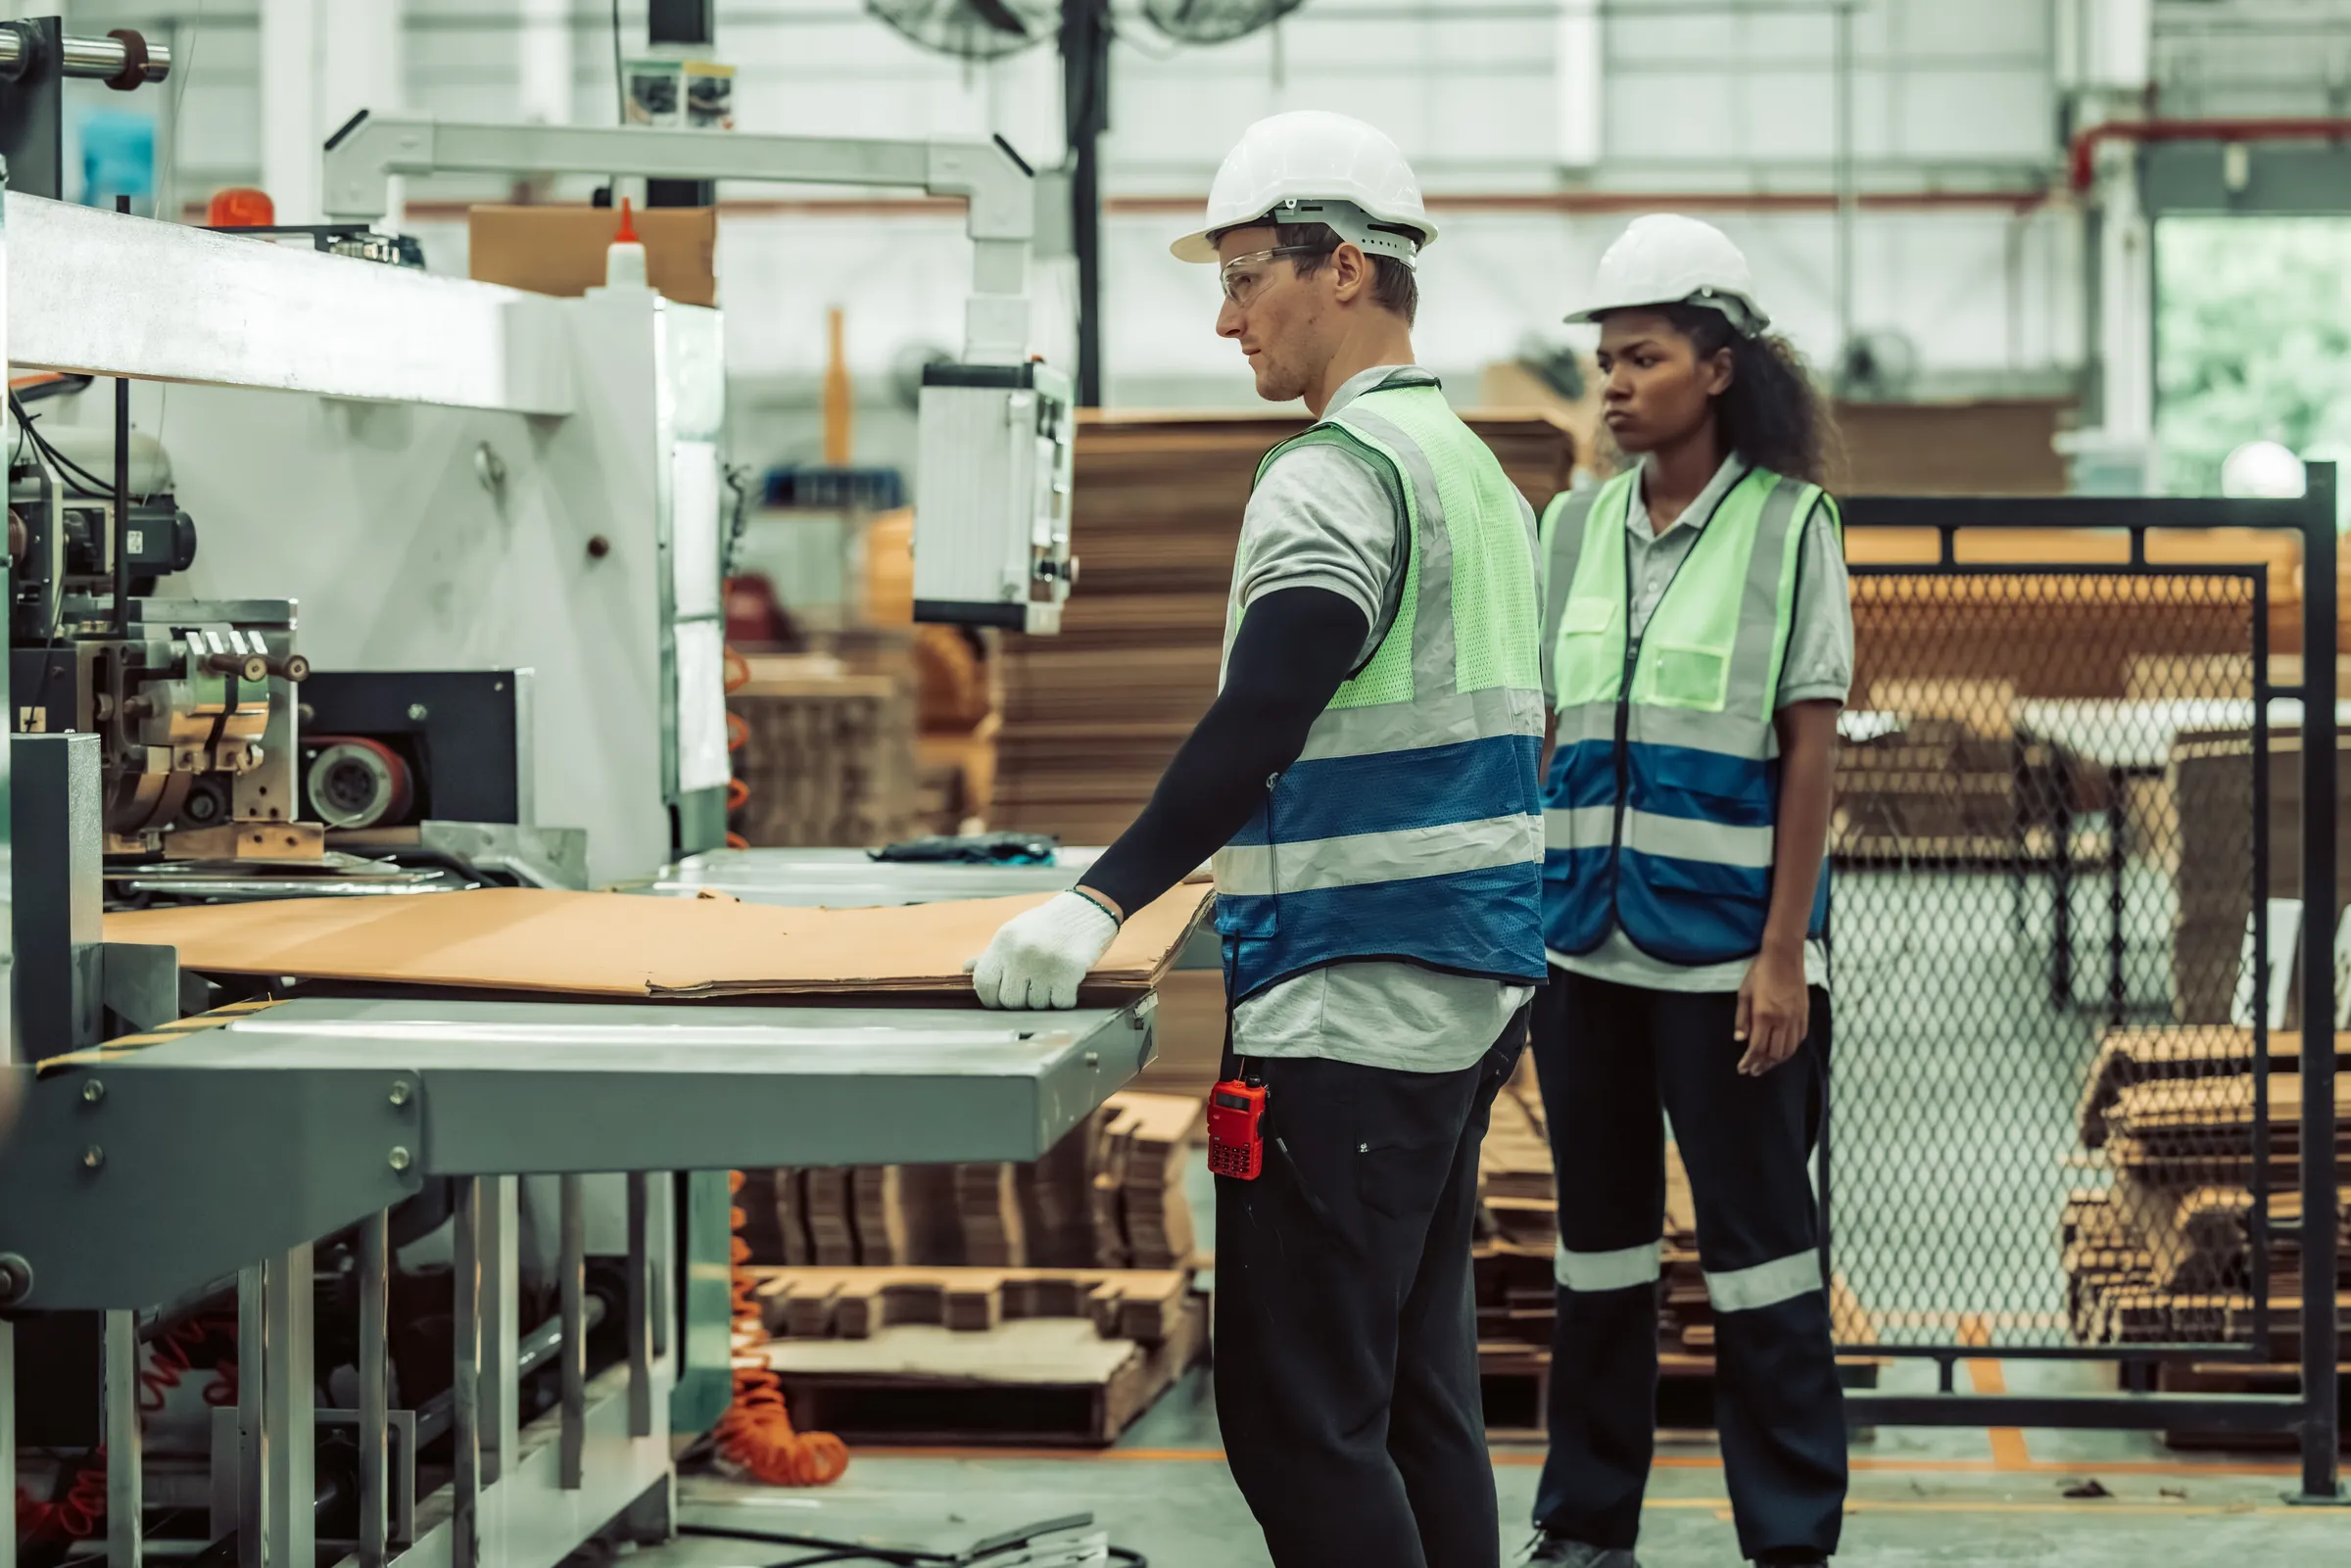
Insurance for manufacturers and trade businesses
Manufacturers, wholesalers, importers and trade businesses run on plant, stock and the products that leave the door with your name on them. The cover has to reach from the factory floor to the customer who uses what you made.
The building, the line and the products that leave it
Property Insurance
Buildings, plant, stock and contents, with the sum insured set to today's replacement cost and the stock declared at the level you hold before your busiest quarter.
Property coverMachinery Breakdown
Sudden failure of production plant, compressors, boilers and refrigeration, with the cost of hiring replacements and expediting parts while the line is down.
Machinery Breakdown coverPublic & Products Liability
Products liability for the goods you make, import or distribute, alongside injury and property damage claims on and off the premises.
Liability coverThe product keeps carrying your name after it leaves the dock
Manufacturing claims tend to arrive from the supply chain rather than the factory.
Imported goods
If you import and resell, Australian consumer law can, in some circumstances, treat you as the manufacturer. The products liability section has to name the imported lines and the countries they are sold into.
Business interruption
A fire in one shed can stop the whole operation. The indemnity period has to allow for replacing long lead plant, and suppliers' and customers' premises extensions are often left off.
Recalls
Pulling a faulty batch from shelves costs money before any injury claim arrives. Recall expenses sit outside a standard liability policy unless they are added.
A press failure, and the orders stacked behind it
An illustrative example of how Ardent can make the difference in a time of need.
The main press on a production line failed. The replacement part carried a long lead time and the line could not run without it, with committed orders building up.
Machinery breakdown cover sat alongside the business interruption section with the machine properly scheduled, and we pressed the insurer to approve expediting costs rather than a standard lead time.
The part was air freighted and the line restarted in a fraction of the time. The repair, the expediting and the lost gross profit were all met.
Responds under Machinery Breakdown
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
What insurers expect to see
Manufacturing policies are rated on turnover, the products declared and the plant on the schedule. We go through the declarations with you each year so the cover matches what is being made now.
- Turnover split by product line and export destination, declared at the current level
- Plant listed with replacement values, including the machines bought or leased since last renewal
- Stock declared at peak, with a declaration basis where levels swing through the year
- An indemnity period long enough to replace the slowest plant to source
- Product recall cover where you supply retailers or food and pharmaceutical markets
- Contract manufacturing and private label agreements read against the liability wording
Our Manufacturing experts
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Mining, aviation, construction, retail and property
Steve has 40 years in insurance, most of it in construction and civil engineering, with underground mining, aviation, national retail and property development alongside. He is one of Ardent's founders, works from inside a client's business and keeps those relationships for the long term.
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
QPIB · Dip. Fin. Serv. (Ins Broking) · Dip. Integrated Risk Management · ANZIIF (Snr Assoc) CIP
Risk management and program design
Stephen co-founded Ardent and has 17 years in insurance, with clients from sole traders to multinational corporates. He works through the risks a business faces and helps decide what to avoid, reduce, retain or insure, balancing cover against cost. He has served on the committee of NIBA's NSW Mentoring Program.
What a client says about Ardent
Great service from Sarah and the team when it came to our insurance claim. Fast acting with the right people for the job and a great overall outcome.