Insurance for property owners and real estate businesses
Commercial landlords, property investors, developers and real estate agencies carry the building, the rent it earns and the advice given about it. Each needs a different policy, and the gaps between them are where claims fall.
The building, the rent and the advice
Property Insurance
Buildings, landlord's fixtures and common areas, with the sum insured set to today's rebuild cost including demolition, professional fees and the time the council takes.
Property coverBusiness Interruption
Loss of rent while a building is repaired after an insured event, for an indemnity period that allows for approvals, rebuilding and re-letting.
Loss of rent coverProfessional Indemnity
For agencies and property managers: claims that a valuation, a lease negotiation or a management decision cost a client money.
Professional Indemnity coverMarket value and rebuild cost are different numbers
Property claims are decided by the sum insured and the lease long before the loss adjuster arrives.
Rebuild cost
A sum insured based on market value or the purchase price has little to do with what a builder will charge to rebuild. Under-insurance clauses then cut the claim in proportion.
Lease and tenant
Leases allocate insurance duties between landlord and tenant. Where both assume the other holds the cover, neither does, and the fit-out or the glass sits uninsured.
Property managers
Trust account fraud, tenant injury and tribunal disputes are managed risks with their own covers. A management agency's professional indemnity does not pick up all three.
A settlement payment that went to the wrong account
An illustrative example of how Ardent can make the difference in a time of need.
Bank details on a settlement instruction were altered after a mailbox was compromised. The funds left the trust account before anyone noticed.
The agency held cyber cover with a funds transfer fraud extension, arranged after we looked at how settlement instructions were being handled.
The loss was met under that extension. The insurer's review also drove a call-back verification step the agency now runs on every settlement.
Responds under Cyber Insurance
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
What insurers expect to see
Property policies are rated on the rebuild cost, the occupancy and the tenants. We go through the schedule with you each year so vacant floors, new tenants and refits are all on the policy.
- Sum insured based on a current rebuild estimate, with demolition and professional fees included
- Occupancy and tenant activities declared, including any hazardous use
- Vacant tenancies reported, with the security conditions that follow met
- Loss of rent cover with an indemnity period that allows for approvals and re-letting
- Strata policies read against what the lot owner still has to insure
- Trust account and fidelity cover where you hold client money
Our Property & Real Estate experts
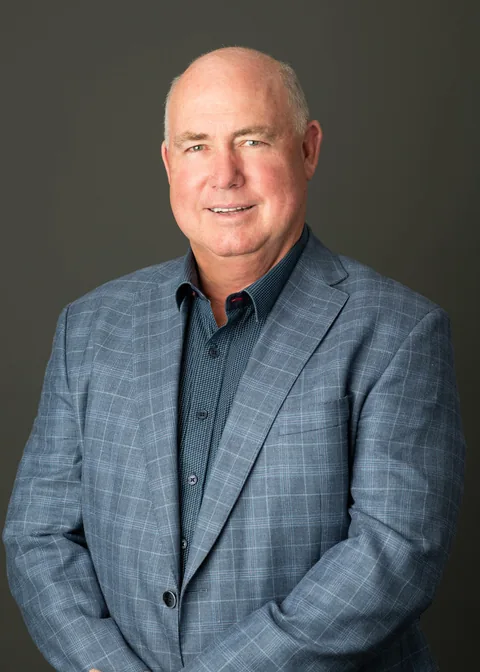
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Mining, aviation, construction, retail and property
Steve has 40 years in insurance, most of it in construction and civil engineering, with underground mining, aviation, national retail and property development alongside. He is one of Ardent's founders, works from inside a client's business and keeps those relationships for the long term.
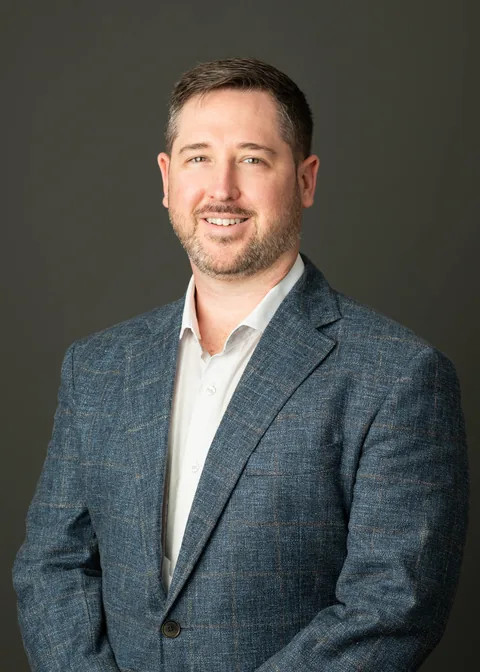
QPIB · Dip. Fin. Serv. (Ins Broking) · Dip. Integrated Risk Management · ANZIIF (Snr Assoc) CIP
Risk management and program design
Stephen co-founded Ardent and has 17 years in insurance, with clients from sole traders to multinational corporates. He works through the risks a business faces and helps decide what to avoid, reduce, retain or insure, balancing cover against cost. He has served on the committee of NIBA's NSW Mentoring Program.
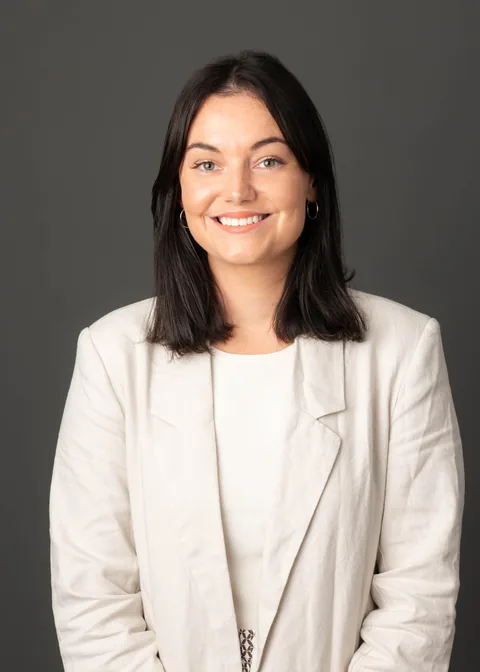
Mid-market businesses and jewellers
Sophie has almost 10 years in insurance broking and is studying for her diploma in insurance broking. She looks after mid-market clients across a range of industries, with a long-standing focus on jewellers. She gets to know each business, its risk profile and its appetite for risk before advising, and keeps in touch through the year.
What a client says about Ardent
Steve and Sophie are very professional and have done a great job in finding the best insurance policy for us. They always arrange for meeting to explain the policy inclusions and make recommendations on best options . We highly recommend them. Thanks Ardent!