Management Liability Insurance
Running a business exposes you personally as a director. A breach, or alleged breach, of the Corporations Act, employment law, or a regulatory obligation can have financial consequences for you personally as well as for the company. Management Liability bundles the key protections in a single, cost-effective policy.
D&O, employment practices and statutory liability in one policy
Management Liability typically bundles three distinct covers, each addressing a different part of the personal and corporate exposure that directors and officers face.
An unfair dismissal claim, and the cost of answering it
An illustrative example of how Ardent can make the difference in a time of need.
A former manager lodged an unfair dismissal application and followed it with a general protections claim. The company was small and had no in-house legal resource.
We notified the employment practices section immediately and had the insurer's panel solicitor appointed that week, before the client ran up costs with their own lawyer.
The matter settled at conciliation. The policy funded the defence costs and the settlement, and the directors were not exposed personally.
This is an illustrative example. Every claim is assessed by the insurer on its own facts and under the terms of the policy.
Our Management Liability experts
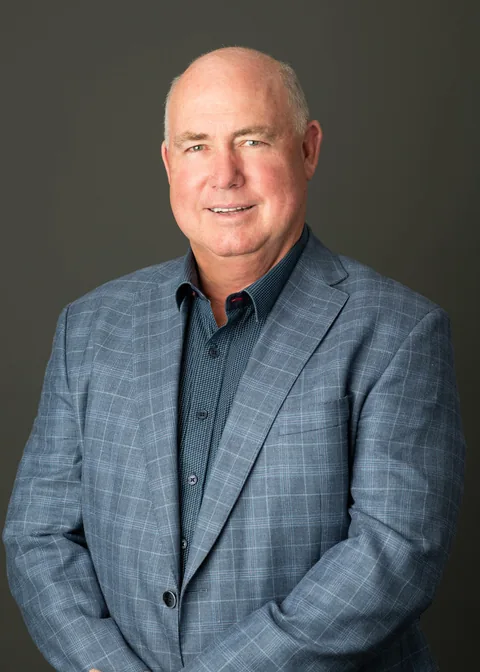
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
Mining, aviation, construction, retail and property
Steve has 40 years in insurance, most of it in construction and civil engineering, with underground mining, aviation, national retail and property development alongside. He is one of Ardent's founders, works from inside a client's business and keeps those relationships for the long term.
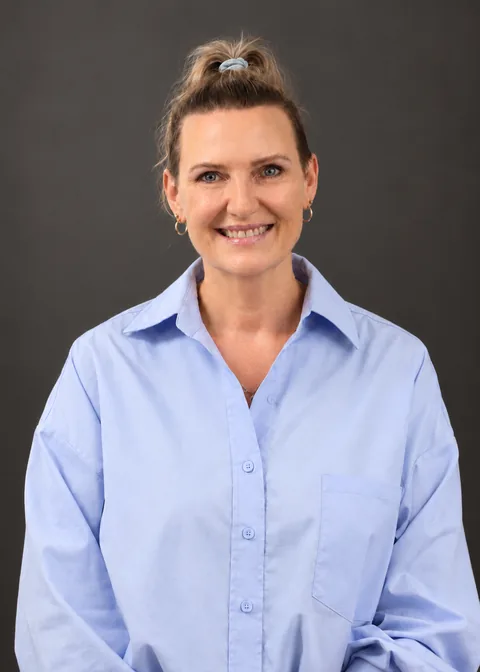
QPIB · Dip. Fin. Serv. (Ins Broking) · ANZIIF (Snr Assoc) CIP
The jewellery trade, childcare and commercial risks
Sarah co-founded Ardent and has more than 30 years in insurance in the UK and Australia, across commercial, property and casualty, professional risks and claims, with a focus on the jewellery trade and childcare. She works with each client to solve problems, plan ahead and see a claim through smoothly.
QPIB · Dip. Fin. Serv. (Ins Broking) · Dip. Integrated Risk Management · ANZIIF (Snr Assoc) CIP
Risk management and program design
Stephen co-founded Ardent and has 17 years in insurance, with clients from sole traders to multinational corporates. He works through the risks a business faces and helps decide what to avoid, reduce, retain or insure, balancing cover against cost. He has served on the committee of NIBA's NSW Mentoring Program.
What a client says about Ardent
Stephen and Ardent Insurance Solutions are unfailingly professional, knowledgeable and courteous.
Gratefully,
Michael
Management Liability FAQ
Any company that has directors, officers, or a management team needs Management Liability insurance. That includes private companies, not-for-profits, and family businesses as well as publicly listed ones. The legal obligations placed on Australian company directors under the Corporations Act, WHS legislation, and employment law expose both the company and its individuals to personal liability. The size of the company does not reduce that exposure. Smaller companies are often more vulnerable because they have fewer resources to fund a legal defence.
Directors & Officers (D&O) insurance is one component of a Management Liability policy. It covers claims against individuals in their management role. A full Management Liability policy bundles D&O with Employment Practices Liability (claims by employees), Statutory Liability (regulatory breaches), and sometimes Crime cover. For most Australian SMEs, the bundled policy covers far more ground than D&O alone.
Statutory Liability cover within a Management Liability policy covers defence costs and insurable penalties arising from unintentional breaches of legislation, including WHS fines and penalty notices. Not all fines are insurable under Australian law, but the defence costs of fighting a regulatory prosecution can be substantial and are generally covered. Ardent reviews your industry's regulatory exposure and sets Statutory Liability limits to suit it.
No. Public liability insurance protects the company against claims from third parties for bodily injury or property damage. It does not protect individual directors from claims brought against them personally, such as breach of duty, misleading conduct, or wrongful dismissal. D&O and Management Liability are the products that protect directors and officers personally. Without them, a director's personal assets, including their home and savings, are exposed.
Common triggers include: unfair dismissal or discrimination claims by current or former employees; regulatory investigations by ASIC, ACCC, the ATO, or WHS authorities; claims by shareholders or creditors alleging mismanagement; failure to meet statutory obligations (payroll tax, superannuation, BAS); data breach notification obligations; and personal liability arising from a company insolvency. The policy responds to both formal legal claims and regulatory investigations, covering defence costs from the outset.